Intt on Karta’s Personal Deposit & Sec 40(b): Tax Treatment
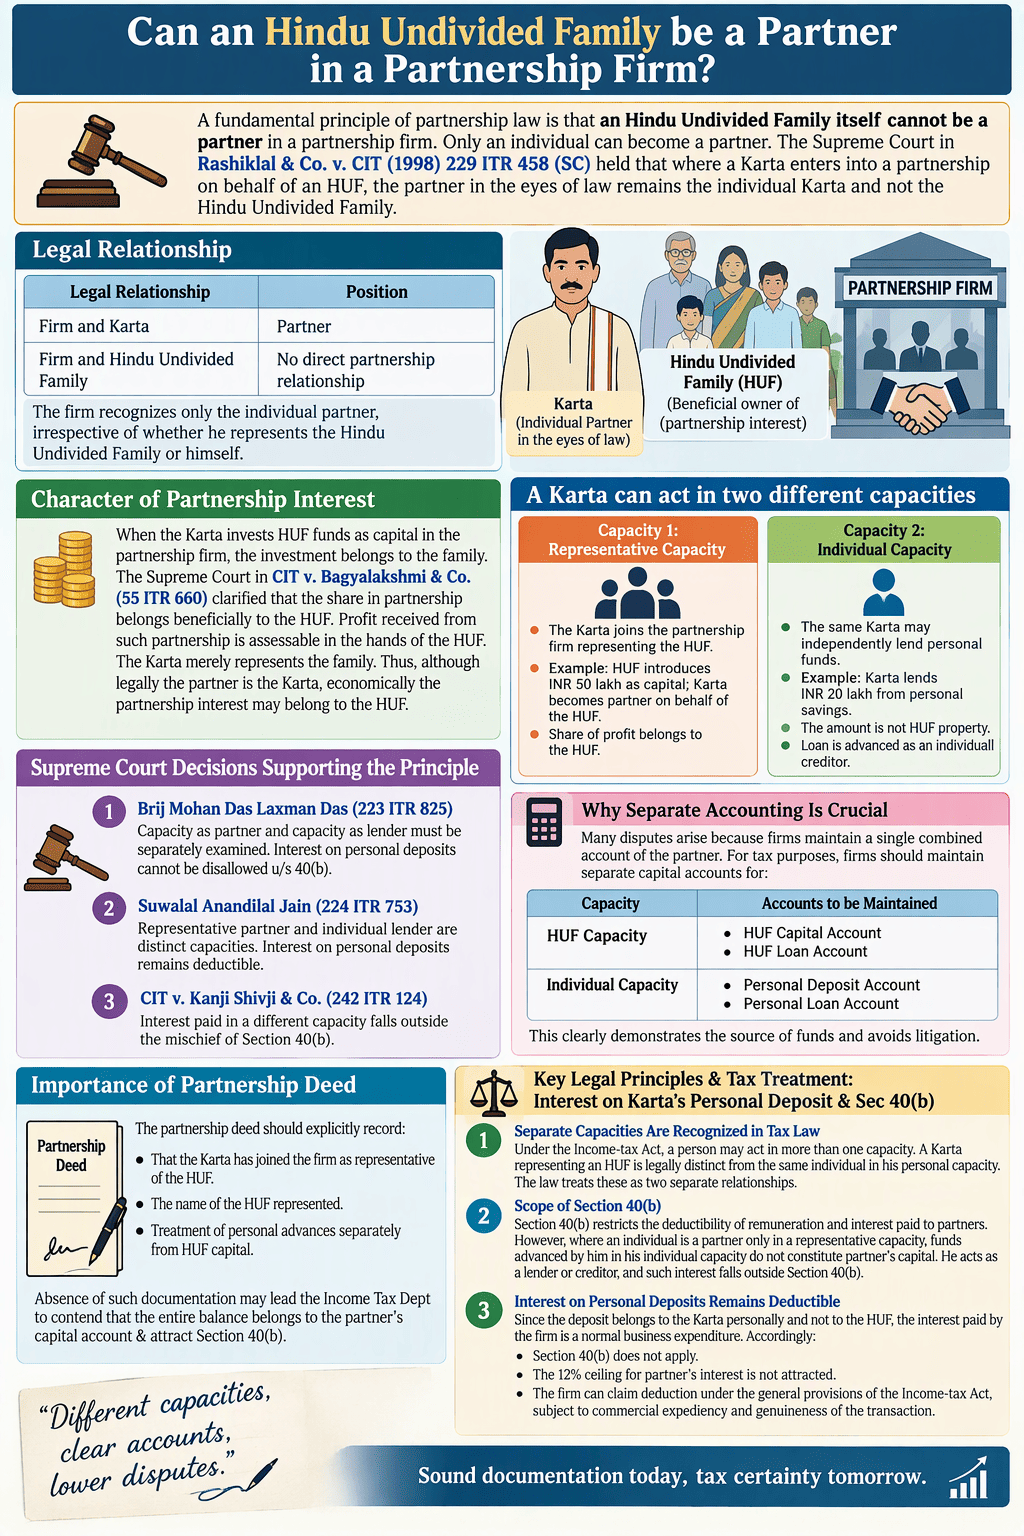
Table of Contents
Karta as Partner: Is Interest on His Personal Deposit Hit by Sec 40(b)
Karta as Partner: Is Interest on His Personal Deposit Hit by Section 40(b) of the Income-tax Act?
In Indian family-owned businesses, it is common for a Hindu Undivided Family (HUF) to participate in a partnership firm through its Karta. Often, the Karta contributes HUF funds as capital in the firm and, separately, may also lend his own personal funds to the same firm. This gives rise to an important tax question:
- If a Karta joins a partnership firm as a representative of the Hindu Undivided Family and also advances his personal funds to the firm, will the interest paid on such personal funds be disallowed or restricted U/S 40(b) of the Income-tax Act, 1961?
- The answer depends upon the capacity in which the Karta deals with the firm.
Understanding Section 40(b) of the Income-tax Act :
- Section 40(b) of the Income-tax Act governs the deductibility of payments made by a partnership firm to its partners. The provision primarily covers Interest paid to partners and Remuneration, salary, bonus, commission paid to partners
- Remuneration is deductible only when paid to a working partner. The partnership deed must specifically authorize remuneration and interest. Interest paid to partners is deductible only up to 12% simple interest per annum, Deductible remuneration is calculated based on the firm’s book profit, Any payment exceeding the limits prescribed u/s 40(b) is not allowable as a deduction. For partnership firms and Limited Liability Partnership, proper structuring of partner remuneration and capital interest can significantly improve tax efficiency while ensuring full compliance with the Income-tax Act, 1961
- Meaning of Book Profit : For the purpose of Section 40(b), Book Profit generally means Net profit as per the Profit & Loss Account, computed under the provisions of the Income-tax Act, before deducting partner remuneration but after considering other allowable adjustments. And Correct computation of book profit is crucial, as the ceiling on partner remuneration is directly linked to this figure.
- Partnership firms and LLP should ensure The partnership deed clearly authorizes remuneration and interest, working partners are identified and documented, Interest rate does not exceed 12% per annum, Remuneration is computed according to the prescribed limits, Separate records are maintained to substantiate payments made to partners and Failure to comply with these requirements may result in disallowance of deductions and an increase in the firm’s taxable income.
Can an Hindu Undivided Family be a Partner in a Partnership Firm?
- A fundamental principle of partnership law is that An Hindu Undivided Family itself cannot be a partner in a partnership firm. Only an individual can become a partner. The Supreme Court in Rashiklal & Co. v. CIT (1998) 229 ITR 458 (SC) held that where a Karta enters into a partnership on behalf of an HUF, the partner in the eyes of law remains the individual Karta and not the Hindu Undivided Family. Therefore:
| Legal Relationship | Position |
| Firm and Karta | Partner |
| Firm and Hindu Undivided Family | No direct partnership relationship |
The firm recognizes only the individual partner, irrespective of whether he represents the Hindu Undivided Family or himself.
Character of Partnership Interest
When the Karta invests Hindu Undivided Family funds as capital in the partnership firm, the investment belongs to the family. The Supreme Court in CIT v. Bagyalakshmi & Co. (55 ITR 660) clarified that The share in partnership belongs beneficially to the HUF. Profit received from such partnership is assessable in the hands of the Hindu Undivided Family. The Karta merely represents the family. Thus, although legally the partner is the Karta, economically the partnership interest may belong to the HUF.
The Concept of Dual Capacity and related Practical Tax Planning Tip
A Karta can act in two different capacities:
- Capacity 1: Representative Capacity : The Karta joins the partnership firm representing the Hindu Undivided Family. Example HUF introduces INR 50 lakh as capital; Karta becomes partner on behalf of the Hindu Undivided Family. And Share of profit belongs to Hindu Undivided Family.
- Capacity 2: Individual Capacity : The same Karta may independently lend personal funds. Example Karta lends INR 20 lakh from personal savings. The amount is not HUF property. Loan is advanced as an individual creditor.
In such a situation, the Karta wears two hats Partner representing Hindu Undivided Family and Individual lender. Tax law recognizes this distinction.
- Explanation 2 to Section 40(b) : To address such situations, Explanation 2 to Section 40(b) provides: Where an individual is a partner in a representative capacity, interest paid to him otherwise than in such representative capacity shall not be taken into account for the purposes of Section 40(b).
- This means Interest Paid on Personal Funds: If Partner represents Hindu Undivided Family in firm, and Loan belongs personally to the Karta, Then Interest is treated as paid to the individual lender. Section 40(b) restriction does not apply. Interest is allowable as business expenditure.
Supreme Court Decisions Supporting the Principle
- Brij Mohan Das Laxman Das (223 ITR 825) : The Supreme Court held that where a partner joins a firm in a representative capacity and separately advances personal funds, interest on such personal deposits cannot be disallowed U/S 40(b). Key Principle is Capacity as partner and capacity as lender must be separately examined.
- Suwalal Anandilal Jain (224 ITR 753) : The Court reaffirmed that Representative partner and individual lender are distinct capacities. And Interest on personal deposits remains deductible.
- CIT v. Kanji Shivji & Co. (242 ITR 124) : The Supreme Court once again upheld the principle that interest paid in a different capacity falls outside the mischief of Section 40(b).
Practical Example
Case A: Personal Deposit by Karta
Mr. X is Karta of X HUF. Capital Contribution : INR 30 lakh introduced from Hindu Undivided Family funds. And Mr. X joins as partner representing HUF. Separate Loan : Mr. X deposits INR 10 lakh from personal bank account. and Firm pays:
- Interest on HUF capital: INR 3,00,000
- Interest on personal deposit: INR 1,00,000
Tax Treatment
| Particulars | Section 40(b) Applicable? |
| Interest on Hindu Undivided Family capital | Yes |
| Interest on personal deposit | No |
- Interest on the personal deposit is fully deductible subject to normal business expenditure provisions.
Case B: Deposit Out of Hindu Undivided Family Funds
- Suppose the additional INR 10 lakh also belongs to Hindu Undivided Family funds. Then Deposit is in representative capacity. And Interest is effectively paid to partner as representative of Hindu Undivided Family. Which may result: Income tax section 40(b) applies. Deduction subject to statutory conditions and limits.
Why Separate Accounting Is Crucial
Many disputes arise because firms maintain a single combined account of the partner. For tax purposes, firms should maintain Separate Capital Accounts for
- Hindu Undivided Family Capacity: HUF Capital Account and Hindu Undivided Family Loan Account
- Individual Capacity: Personal Deposit Account and Personal Loan Account. This clearly demonstrates the source of funds and avoids litigation.
Importance of Partnership Deed
- The partnership deed should explicitly record That the Karta has joined the firm as representative of the Hindu Undivided Family. The name of the Hindu Undivided Family represented. And Treatment of personal advances separately from HUF capital. Absence of such documentation may lead the Income Tax Dept to contend that the entire balance belongs to the partner’s capital account & attract Section 40(b).
Key Legal Principles & Tax Treatment: Interest on Karta’s Personal Deposit & Sec 40(b):
- Separate Capacities Are Recognized in Tax Law: Under the Income-tax Act, a person may act in more than one capacity. A Karta representing an HUF is legally distinct from the same individual dealing with the firm in his personal capacity. Therefore, the Karta may Participate in the firm as a partner representing the HUF; and independently lend or deposit his personal funds with the firm as an individual creditor. The law treats these as two separate relationships.
- Scope of Section 40(b): Section 40(b) restricts the deductibility of remuneration and interest paid by a firm to its partners. However, where an individual is a partner only in a representative capacity, any funds advanced by that person in his individual capacity do not constitute partner’s capital. In such circumstances, the individual acts as a lender or creditor to the firm rather than as a partner in respect of those funds. Consequently, the interest paid on such individual deposits is not regarded as interest paid to a partner for the purposes of Section 40(b).
- Interest on Personal Deposits Remains Deductible : Since the deposit belongs to the Karta personally and not to the HUF represented by him, the interest paid by the firm is treated as a normal business expenditure. Accordingly: Section 40(b) does not apply. The 12% ceiling prescribed for partner’s interest is not attracted. The firm can claim deduction for such interest under the general provisions of the Income-tax Act, subject to commercial expediency and genuineness of the transaction.
Practical Compliance Tips for Hindu Undivided Family.
To avoid disputes during tax assessments:
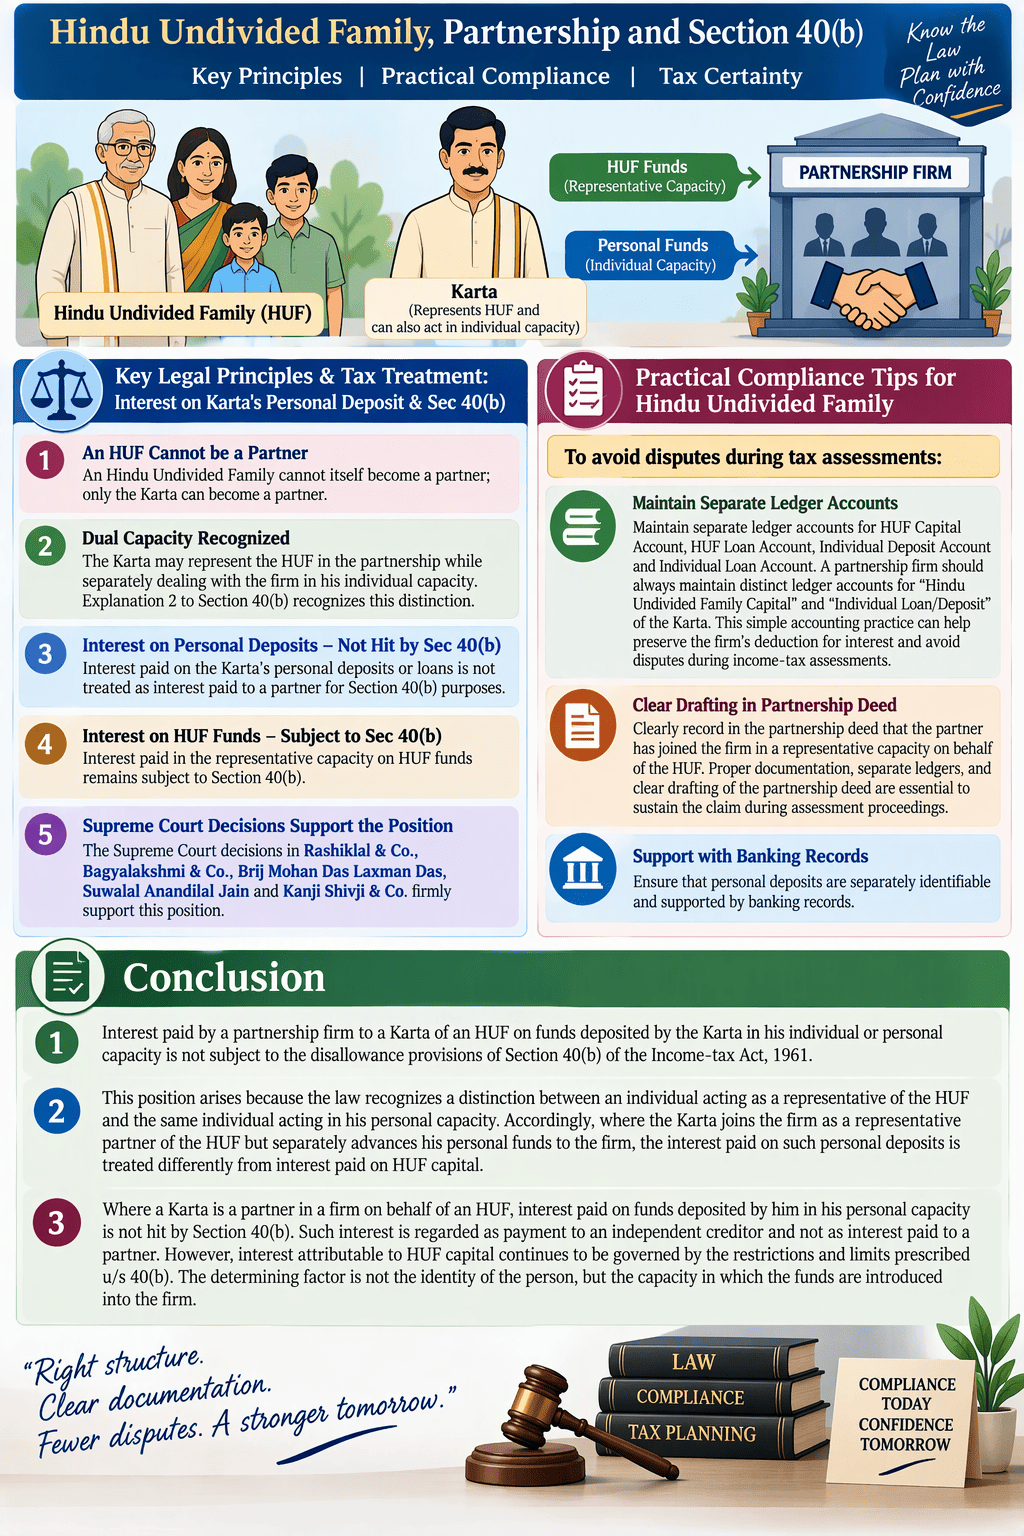
- Maintain separate ledger accounts for HUF Capital Account, HUF Loan Account, Individual Deposit Account and Individual Loan Account. A partnership firm should always maintain distinct ledger accounts for ” Hindu Undivided Family Capital” and “Individual Loan/Deposit” of the Karta. This simple accounting practice can help preserve the firm’s deduction for interest and avoid disputes during income-tax assessments.
- Clearly record in the partnership deed that the partner has joined the firm in a representative capacity on behalf of the HUF. Proper documentation, separate ledgers, and clear drafting of the partnership deed are essential to sustain the claim during assessment proceedings.
- Ensure that personal deposits are separately identifiable and supported by banking records.
- An Hindu Undivided Family cannot itself become a partner; only the Karta can become a partner.
- The Karta may represent the Hindu Undivided Family in the partnership while separately dealing with the firm in his individual capacity. Explanation 2 to Section 40(b) recognizes this distinction.
- Interest paid on the Karta’s personal deposits or loans is not treated as interest paid to a partner for Section 40(b) purposes.
- Interest paid in the representative capacity on Hindu Undivided Family funds remains subject to Section 40(b).
- Supreme Court decisions in **Rashiklal & Co., Bagyalakshmi & Co., Brij Mohan Das Laxman Das, Suwalal Anandilal Jain and Kanji Shivji & Co. firmly support this position.
Conclusion
- Interest paid by a partnership firm to a Karta of a Hindu Undivided Family (HUF) on funds deposited by the Karta in his individual or personal capacity is not subject to the disallowance provisions of Section 40(b) of the Income-tax Act, 1961.
- This position arises because the law recognizes a distinction between an individual acting as a representative of the HUF and the same individual acting in his personal capacity. Accordingly, where the Karta joins the firm as a representative partner of the HUF but separately advances his personal funds to the firm, the interest paid on such personal deposits is treated differently from interest paid on HUF capital.
- Where a Karta is a partner in a firm on behalf of an Hindu Undivided Family, interest paid on funds deposited by him in his personal capacity is not hit by Section 40(b). Such interest is regarded as payment to an independent creditor and not as interest paid to a partner. However, interest attributable to Hindu Undivided Family capital continues to be governed by the restrictions and limits prescribed u/s 40(b). The determining factor is not the identity of the person, but the capacity in which the funds are introduced into the firm.
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.