NRI/POI /OCI Gifting Immovable Property to Resident Indian
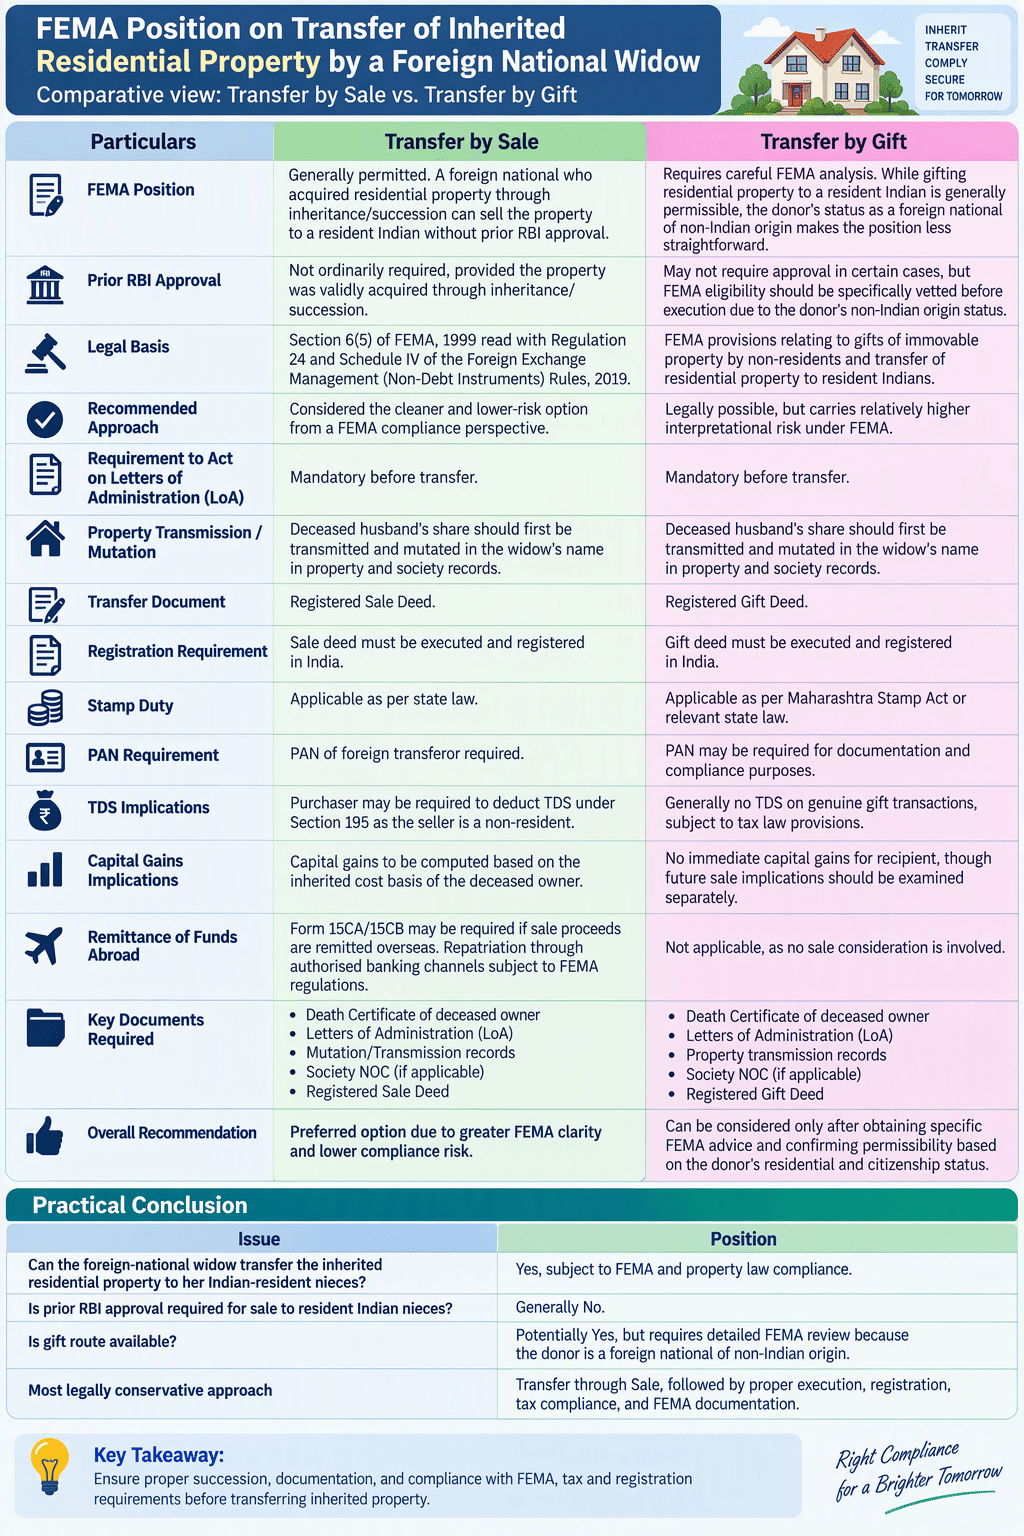
Table of Contents
FEMA & I Tax Implication When Gifting Immovable Property to a Resident Indian
Is NRI/POI/OCI may gift immovable property to a resident Indian without RBI Approval ?
In this query case: The OCI holder died in 2024 without a Will. His US citizen spouse applied to the court. An NRI or PIO may gift immovable property to a resident Indian without approval. However, a foreign national of non-Indian origin requires prior RBI approval.” If this interpretation is applied strictly, then your case becomes sensitive because:
- Deceased husband was an OCI holder.
- Widow is a US citizen of foreign origin (not OCI, not PIO, based on facts provided).
- The widow acquired the property through succession/inheritance.
- She proposes to gift her share to resident Indian nieces.
- The Mumbai High Court granted Letters of Administration declaring her entitled to administer his estate and, as you mentioned, recognizing her as the sole legal heir to his share in the flat.
Are nieces covered under “relative” definition?
FEMA Definition :
For FEMA purposes, “relative” refers to the definition under Section 2(77) of the Companies Act, 2013. Under that definition:
- Brother’s daughter → Relative
- Sister’s daughter → Relative
Accordingly, the husband’s nieces would generally qualify as relatives through the relationship with the deceased husband.
Income-tax Definition
For income-tax purposes, Section 56 uses the definition of “relative” which specifically includes:
- brother’s or sister’s descendants,
- spouse’s brother’s or sister’s descendants.
Thus, a gift received by the nieces from their paternal/maternal aunt through the husband’s side should generally fall within the exempt relative category. The exact tax position should nevertheless be reviewed based on the family tree and documentation. (Income-tax analysis is separate from FEMA.)
Comparison: Gift vs. Sale
TRANSITION OPTIONS
│
┌──────────────────────────┴──────────────────────────┐
▼ ▼
GIFT DEED SALE DEED
───────────────── ─────────────────
- No RBI Approval Needed • No RBI Approval Needed
- Income Tax Exempt for Nieces • Subject to TDS & Capital Gains Tax
- Standard Stamp Duty applies • Standard Stamp Duty applies
- Best option given intent to transfer • Proceeds can be repatriated up to
without financial consideration $1M USD/year under LRS / NRO route
Conservative recommendation: Transfer through sale is legally cleaner and carries lower FEMA interpretational risk. Completed without prior RBI approval, but the position differs depending on whether the aunt transfers the property by sale or by gift.
FEMA Position on Transfer of Inherited Residential Property by a Foreign National Widow
| Particulars | Transfer by Sale | Transfer by Gift |
|
FEMA Position
|
Generally permitted. A foreign national who acquired residential property through inheritance/succession can sell the property to a resident Indian without prior RBI approval. | Requires careful FEMA analysis. While gifting residential property to a resident Indian is generally permissible, the donor’s status as a foreign national of non-Indian origin makes the position less straightforward. |
| Prior RBI Approval | Not ordinarily required, provided the property was validly acquired through inheritance/succession. | May not require approval in certain cases, but FEMA eligibility should be specifically vetted before execution due to the donor’s non-Indian origin status. |
| Legal Basis | Section 6(5) of FEMA, 1999 read with Regulation 24 and Schedule IV of the Foreign Exchange Management (Non-Debt Instruments) Rules, 2019. | FEMA provisions relating to gifts of immovable property by non-residents and transfer of residential property to resident Indians. |
| Recommended Approach | Considered the cleaner and lower-risk option from a FEMA compliance perspective. | Legally possible, but carries relatively higher interpretational risk under FEMA. |
| Requirement to Act on Letters of Administration (LoA) | Mandatory before transfer. | Mandatory before transfer. |
| Property Transmission / | Deceased husband’s share should first be transmitted and mutated in the widow’s name in property and society records. | Deceased husband’s share should first be transmitted and mutated in the widow’s name in property and society records. |
| Transfer Document | Registered Sale Deed. | Registered Gift Deed. |
| Registration Requirement | Sale deed must be executed and registered in India. | Gift deed must be executed and registered in India. |
| Stamp Duty | Applicable as per state law. | Applicable as per Maharashtra Stamp Act or relevant state law. |
| PAN Requirement | PAN of foreign transferor required. | PAN may be required for documentation and compliance purposes. |
| TDS Implications | Purchaser may be required to deduct TDS under Section 195 as the seller is a non-resident. | Generally no TDS on genuine gift transactions, subject to tax law provisions. |
| Capital Gains Implications | Capital gains to be computed based on the inherited cost basis of the deceased owner. | No immediate capital gains for recipient, though future sale implications should be examined separately. |
| Remittance of Funds Abroad | Form 15CA/15CB may be required if sale proceeds are remitted overseas. Repatriation through authorised banking channels subject to FEMA regulations. | Not applicable, as no sale consideration is involved. |
| Key Documents Required | • Death Certificate of deceased owner • Letters of Administration (LoA) • Mutation/Transmission records • Society NOC (if applicable) • Registered Sale Deed |
• Death Certificate of deceased owner • Letters of Administration (LoA) • Property transmission records • Society NOC (if applicable) • Registered Gift Deed |
| Overall Recommendation | Preferred option due to greater FEMA clarity and lower compliance risk. | Can be considered only after obtaining specific FEMA advice and confirming permissibility based on the donor’s residential and citizenship status. |
Practical Conclusion
| Issue | Position |
| Can the foreign-national widow transfer the inherited residential property to her Indian-resident nieces? | Yes, subject to FEMA and property law compliance. |
| Is prior RBI approval required for sale to resident Indian nieces? | Generally No. |
| Is gift route available? | Potentially Yes, but requires detailed FEMA review because the donor is a foreign national of non-Indian origin. |
| Most legally conservative approach | Transfer through Sale, followed by proper execution, registration, tax compliance, and FEMA documentation. |
Is Prior Approval or Intimation Required from the RBI?
When the Property Holding via Inheritance: U/s 6(5) of FEMA, 1999, a person resident outside India can hold or transfer immovable property in India if such property was inherited from a person resident in India. Because the property was inherited from her deceased husband (an OCI who inherited it from his Indian resident mother), the foreign national spouse legally acquires this share.
Transfer by Sale or Gift:
Under the Foreign Exchange Management (Non-debt Instruments) Rules, 2019 [Regulation 24 & Schedule IV]:
Transfer by Sale :
- A foreign national (person resident outside India) can sell residential property in India to a person resident in India without prior RBI approval. The foreign-national widow (US citizen, non-Indian origin) would acquire the property through succession from her deceased husband’s inherited share. FEMA permits a person resident outside India to hold immovable property acquired by inheritance/succession, and transfer of residential property to a person resident in India is generally permissible. No separate prior RBI approval is ordinarily required for such transfer. However, before any transfer:
-
- The Letters of Administration (LoA) should be appropriately acted upon.
- The deceased husband’s share should be mutated/transmitted in her favour in the property records/society records.
- The sale deed should be executed and registered in India.
- Execution and registration of Sale Deed. PAN of foreign transferor. Purchasers may need to deduct TDS under section 195 since the seller is a non-resident. Capital gains computation to be examined from the deceased OCI holder’s inherited cost basis. Form 15CA/15CB may be relevant if sale proceeds are remitted overseas. Repatriation of funds through authorized banking channels subject to FEMA regulations.
In case by Gift:
General Permission (Automatic Route) allows a non-resident to gift residential immovable property located in India to a Person Resident in India. This requires more careful FEMA analysis. Under the RBI/FEMA framework, gifts of immovable property by a non-resident are generally permitted only in specified situations. The nieces are Indian residents, and the property is residential. While a gift to a resident Indian is generally permitted under FEMA for residential property, the fact that the donor is a foreign national of non-Indian origin rather than an NRI/OCI makes the matter less straightforward. So if transferred by Gift than
- Registered Gift Deed. Property mutation thereafter. Stamp duty as applicable in Maharashtra. Maintain complete succession documents:
- Death Certificate of OCI holder.
- Letters of Administration.
- Property transmission records.
- Society NOC, if applicable.
- FEMA eligibility of the gift should be specifically vetted before execution because of the donor’s status as a foreign national of non-Indian origin.
Basic Rules & Conditions for Gifting Property by an NRI/PIO/OCI to a Resident Indian
Following are key Rules & Conditions for Gifting Property by an NRI/PIO/OCI to a Resident Indian
Basic Rules & Conditions for Gifting Property by an NRI/PIO/OCI to a Resident Indian
| S. No. | Rule / Condition | Details |
| 1 | Eligible Property Types | An NRI, PIO, or OCI can gift only residential or commercial immovable property located in India to a resident Indian. |
| 2 | Restrictions on Agricultural Property | Agricultural land, plantation property, and farmhouses are subject to FEMA restrictions and generally cannot be gifted freely. Specific provisions apply based on the residential status of the donor and recipient. |
| 3 | No Cash Transactions | All expenses related to the transfer, including stamp duty, registration fees, and incidental charges, must be paid through authorized banking channels such as NRE, NRO, or FCNR(B) accounts. Cash payments are not permitted. |
| 4 | Registered Gift Deed Mandatory | The transfer is legally valid only when a gift deed is duly executed and registered in accordance with the provisions of the Indian Registration Act. |
| 5 | Restrictions for Certain Countries | Citizens or entities from Pakistan, Bangladesh, Sri Lanka, Afghanistan, China, Iran, Nepal, Bhutan, Hong Kong, Macau, and North Korea are required to obtain prior RBI approval before undertaking such transactions. |
Before gifting immovable property in India, an NRI/PIO/OCI should ensure FEMA compliance, execute a registered gift deed, route all payments through approved banking channels, and verify whether any RBI approval requirements apply.
Summary on Prior Approval or Intimation Required from the RBI Approval:
No prior permission or intimation to the RBI is required for transferring a residential flat share to resident Indian citizens by way of Sale or Gift, provided the recipients (the nieces) are Indian residents. In practice, many professionals prefer either a sale to the nieces, or obtaining a specific FEMA opinion/AD Bank confirmation before proceeding with a gift, because the donor is not an OCI/NRI but a foreign national who acquired the property through succession.
Definition of “Relatives” under FEMA vs. Income Tax Act
The applicability of the “Relative” definition depends on whether you are looking at FEMA compliance or Income Tax consequences:
Under FEMA
- Definition Source: FEMA adopts the definition of “relative” from Section 2(77) of the Companies Act, 2013.
- Does it include Nieces? No. Under the Companies Act, “relatives” are restricted to spouses, parents, children, siblings, and immediate lineals. Nieces are not covered.
- Does this matter for FEMA? No. FEMA permits the transfer/gifting of residential property by a non-resident to any Person Resident in India (whether they are a relative or a non-relative). Thus, the definition of relative does not restrict the FEMA transaction itself.
Under the Income Tax Act, 1961 (Section 56(2)(x))
- Definition Source: Section 56(2)(x) of the Income Tax Act defines “relative” for tax exemptions on gifts received without consideration.
Does it include Nieces?
- Under Section 56(2)(x), a “relative” includes the brother/sister of parents.
- From the nieces’ perspective, their deceased uncle was their father’s/mother’s brother (a relative). However, the Foreign National Aunt (the uncle’s wife) is the spouse of the parent’s brother.
- The Income Tax Act considers the spouse of a brother/sister of a parent as a defined relative.
Tax Implications for the Recipient – Tax Impact based on Transfer Mode:
| Mode | Income Tax & Stamp Duty Impact |
| Gift Deed | Tax-Exempt for Nieces: Since the aunt qualifies as a relative under Sec 56(2)(x) of the Income Tax Act, the gift received by the nieces is exempt from income tax.
Stamp Duty: Standard Maharashtra Stamp Duty rates for non-lineal relatives (approx. 3%–5% + surcharges) will apply. (The concessional 200 INR stamp duty in Maharashtra applies primarily to direct linear descendants/lineal ascendants/siblings).
|
| Sale Deed | Taxable Capital Gains: If transferred via Sale, the foreign national aunt will be subject to Capital Gains Tax in India (TDS under Sec 195 will apply). Since she inherited the property, her cost of acquisition and holding period will trace back to the deceased husband / original resident owner. |
-
Other Required Legal & Regulatory Compliances
Before or during the execution of the transfer, ensure the following steps are completed:
Title Mutation & Registration:
The spouse must first register the Letter of Administration (LoA) with the Registrar/Sub-Registrar of Assurances in Mumbai and update the municipal records/society share certificate to reflect her name.
Power of Attorney (PoA):
Given her age (70+) and residence in the US, she does not need to travel to India. She can execute a Specific Power of Attorney (PoA) in the US in favor of a trusted representative in Mumbai to execute and register the Gift/Sale Deed.
- The PoA must be Notarized and Apostilled in the USA (or executed at the Indian Consulate).
- Upon reaching Mumbai, the PoA must be adjudicated and stamped at the Collector of Stamps office.
PAN Card for Foreign National: The foreign national spouse must possess or apply for an Indian Permanent Account Number card for property registration and tax compliance.
Society Approvals: An application to the Co-operative Housing Society for transfer of the 50% shareholding, along with NOC/Forms and society transfer fees.
Key takeaway for above fact pattern
Based on the FEMA position above, there is a reasonable argument that:
- Sale to the resident nieces can be undertaken without RBI approval, subject to FEMA, tax and registration compliances.
- Gift to the resident nieces may require prior RBI approval because the donor is a foreign national of non-Indian origin and not an NRI/OCI/PIO.
Relatives issue
- For FEMA purposes, the “relative” concept is generally linked to the definition adopted from the Companies Act, 2013, whereas for taxation of gifts, the definition under Section 56 of the Income-tax Act, 1961 is relevant. The two statutes operate independently.
“An NRI or PIO may gift immovable property to a resident Indian without approval. However, a foreign national of non-Indian origin requires prior RBI approval.” If this interpretation is applied strictly, then your case becomes sensitive because:
- Deceased husband was an OCI holder.
- Widow is a US citizen of foreign origin (not OCI, not PIO, based on facts provided).
- The widow acquired the property through succession/inheritance.
- She proposes to gift her share to resident Indian nieces.
In such circumstances, the FEMA issue is not whether she can hold the inherited property. She can generally hold property acquired through inheritance/succession. The issue is whether a gift by a foreign national of non-Indian origin to resident Indians falls within the automatic route or requires approval.
Conservative legal view Clarification on Section 2(h)
Under Indian statute frameworks relevant to FEMA Section 2(h) refers to: General Definition of “Relative” under FEMA — Section 2(u) Under FEMA, the term “relative” is defined under Section 2(u), which states that a relative has the same meaning as assigned to it in Section 2(77) of the Companies Act, 2013.
Specific Impact on this Case (Aunt to Nieces)
Income Tax Act Definition —
Important Correction for Taxability Under Section 56(2)(x) of the Income Tax Act: The list of relatives is one-way/asymmetric. For the nieces receiving the gift, a relative includes the “brother or sister of either of the parents” (their deceased Uncle) AND the “spouse of such brother/sister” (their Foreign National Aunt). Conclusion for Nieces: The gift received by the nieces from their aunt is 100% EXEMPT from Income Tax.
FEMA Applicability — Relative Status Does Not Matter:
Under FEMA / Non-Debt Instruments (NDI) Rules, 2019, general permission is granted to any person resident outside India to gift residential property to ANY Person Resident in India. Conclusion for FEMA: You do NOT need the recipient to qualify as a “relative” under FEMA/Companies Act to execute a valid gift deed. Transferring to an Indian resident niece via gift is fully permissible under the automatic route without prior RBI approval.
Updated Action on Conservative legal view Clarification
| Regulatory Aspect | Is “Relative” status required? | Status for Aunt → Niece | Result / Liability |
| RBI / FEMA Regulations | No. Gift allowed to any Resident Indian. | Fully Permissible | No RBI Approval Required |
| Income Tax (Sec 56(2)(x)) | Yes. To claim gift tax exemption. | Aunt qualifies as relative (spouse of parent’s brother) | 0% Income Tax for Nieces |
| Maharashtra Stamp Duty | Yes. For 200 INR concessional rate (only for direct lineals/siblings). | Niece is not a direct lineal descendant/sibling. | Standard Stamp Duty Applies (~3%–5%) |
What set to be taken care while NRI/POI/OCI may gift immovable property to a resident Indian without RBI Approval
- First complete transmission of the deceased OCI holder’s share into the widow’s name. A sale to the resident nieces is the most robust FEMA route. If the family intends to avoid consideration and proceed by gift, obtain a specific FEMA opinion from a specialist counsel or confirmation through the Authorized Dealer Bank before execution, given the donor’s foreign-national status.
- This is a nuanced FEMA succession issue involving a foreign-national widow rather than an OCI/NRI transferee, and I would recommend a detailed review of the LoA and the property title documents before a final opinion is issued.
- LoA means Letters of Administration. It is an order issued by a competent court (in your case, the Mumbai High Court) authorizing a person to administer and deal with the estate of a deceased person who died without leaving a valid Will (intestate).
- The LoA serves as legal authority for Mutation/transmission of the deceased’s share in property records. Updating society records. Dealing with banks, investments, and other assets. Selling, gifting, or otherwise transferring the inherited property (subject to FEMA, stamp duty, and registration requirements).
- However, obtaining the LoA and completing the property transmission/mutation are separate steps. Even after obtaining the LoA, the widow should ensure that the deceased owner’s share is recorded in her name in the municipal/society/revenue records before executing a gift or sale transaction.
- For the FEMA issue in your query, the exact wording of the LoA and the succession documents would be important because the widow is a foreign national of non-Indian origin, which makes the FEMA analysis more nuanced than a typical NRI/OCI succession case.
Practical Takeaway & Recommendation
- Before gifting property in India, NRIs/PIOs/OCIs should ensure compliance with FEMA regulations, execute a properly registered gift deed, route all payments through authorized banking channels, and evaluate the tax implications based on the recipient’s relationship with the donor.
- We would advise Complete mutation/transmission of the deceased OCI holder’s share in favour of the widow based on the Letters of Administration. If the objective is to transfer the property with minimum FEMA risk, consider a sale deed in favour of the nieces. If the family prefers a gift deed, obtain a formal FEMA opinion and, if necessary, approach the Authorized Dealer Bank/RBI route before execution because of the widow’s status as a foreign national of non-Indian origin.
- In fact, this is one of those cases where the answer turns on the widow’s exact immigration status (US citizen only, OCI cardholder, or otherwise) and the wording of the succession documents. Therefore, before giving a final written opinion, I would verify the current FEMA provisions applicable to inheritance-based ownership by a foreign national and the RBI approval position for gifting by such person.
FEMA, Income Tax & Stamp Duty Implications (Aunt to Niece Transfer)
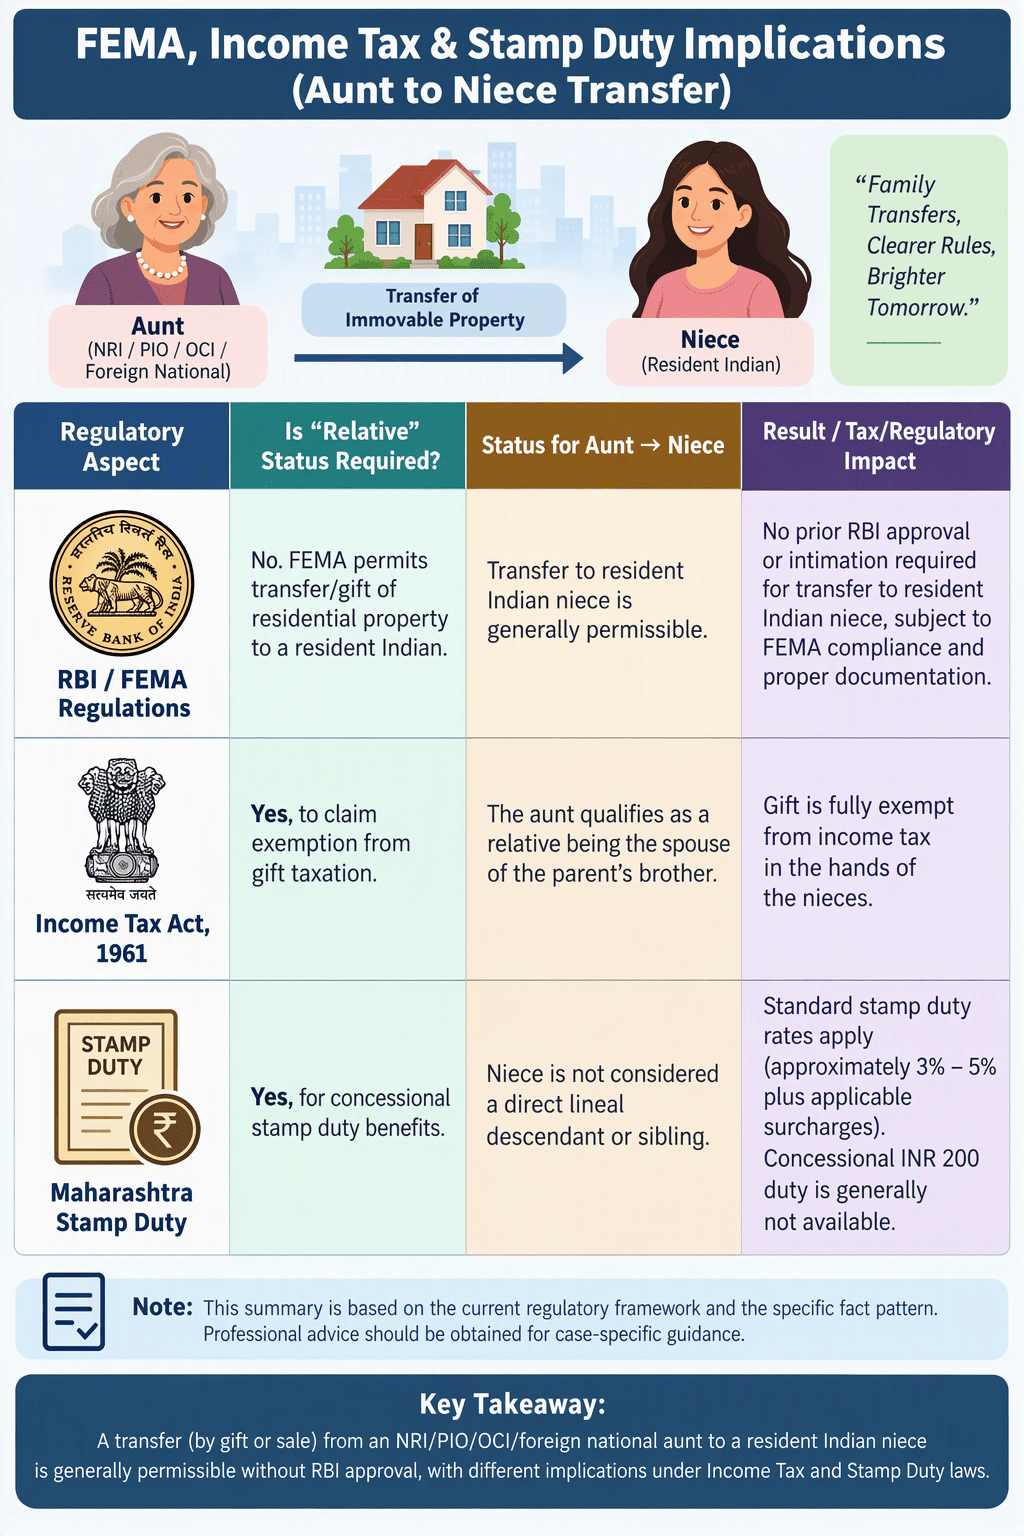
| Regulatory Aspect | Is “Relative” Status Required? | Status for Aunt → Niece | Result / Tax/Regulatory Impact |
| RBI / FEMA Regulations | No. FEMA permits transfer/gift of residential property to a resident Indian. | Transfer to resident Indian niece is generally permissible. | No prior RBI approval or intimation required for transfer to resident Indian niece, subject to FEMA compliance and proper documentation. |
| Income Tax Act, 1961 | Yes, to claim exemption from gift taxation. | The aunt qualifies as a relative being the spouse of the parent’s brother. | Gift is fully exempt from income tax in the hands of the nieces. |
| Maharashtra Stamp Duty | Yes, for concessional stamp duty benefits. | Niece is not considered a direct lineal descendant or sibling. | Standard stamp duty rates apply (approximately 3%–5% plus applicable surcharges). Concessional INR 200 duty is generally not available |
Practical Recommendation
| Situation | Recommended Course of Action |
| Transfer through Sale | Most legally robust and conservative approach from a FEMA compliance perspective. |
| Transfer through Gift | Obtain a specific FEMA opinion from an expert counsel or confirmation from the Authorized Dealer (AD) Bank before execution, particularly where the donor is a foreign national of non-Indian origin. |
| Before Any Transfer | Complete LoA implementation, property mutation, society formalities, and title verification. |
Even where RBI approval is not required, the transfer should be undertaken only after completing succession formalities, mutation of property records, verification of title documents, and a careful FEMA review, particularly when the donor is a foreign national who acquired the property through inheritance.
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.