TDS on Purchase of Property from NRI: PAN-Based Compliance
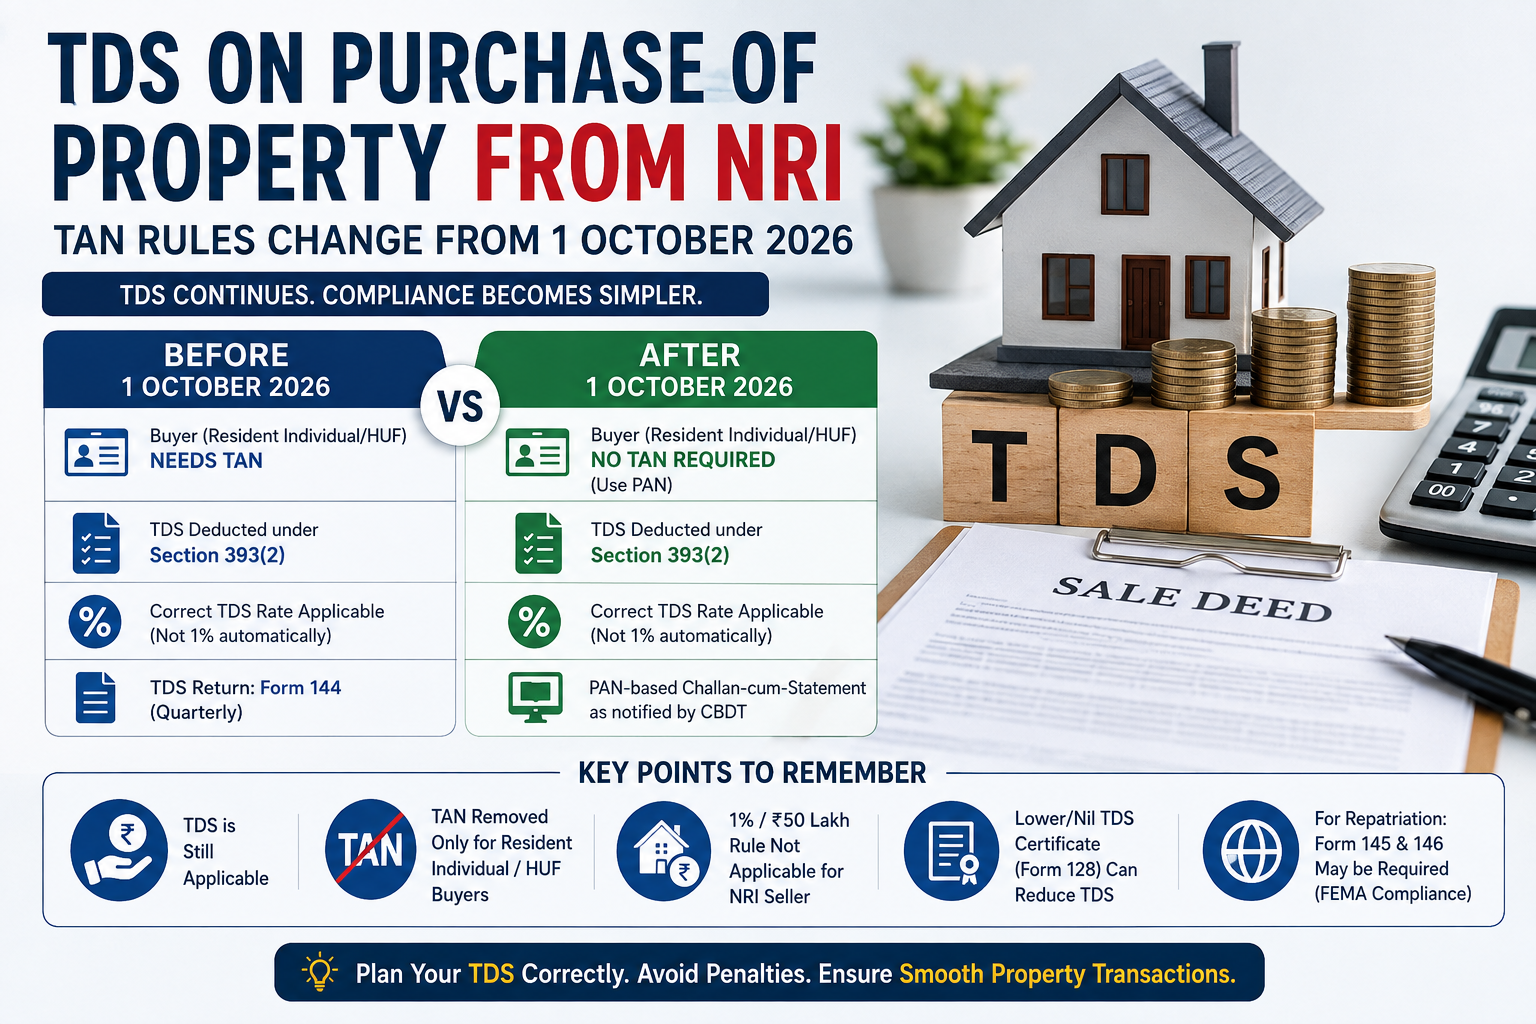
Table of Contents
TAN Requirement Ends From 1 October 2026, but NRI Property TDS Continues
The Income-tax (Fifth Amendment) Rules, 2026 bring a welcome compliance simplification. From 1 October 2026, a resident individual or HUF buying immovable property from a non-resident will no longer need a TAN. The buyer can instead deduct and deposit tax under their own PAN through the challan-cum-statement in Form No. 141, using the newly inserted Schedule E.
However, the change is procedural, not substantive. Buyers and NRI sellers should keep the following in mind:
- TDS continues. The obligation to deduct tax under section 393(2) remains fully in force; only the mode of compliance has changed.
- The 1% resident-seller rate does not apply. TDS is deducted at the rates in force on the nature of the capital gain (long-term or short-term), plus surcharge and cess.
- INR 50 lakh threshold does not apply. TDS is required on any amount paid to a non-resident seller, whatever the value of the property.
- Lower deduction certificates can make a real difference. Deducting on the full consideration often results in excess withholding. A certificate u/s 395(1), (2) or (6), obtained before payment, can bring TDS in line with the actual tax liability.
- Timing determines the process. For payments up to 30 September 2026, the existing TAN-based mechanism and regular non-resident TDS statement (Form 144) continue to apply, and Form 141 cannot be used for a non-resident seller. From 1 October 2026, Form 141 (Schedule E) becomes available to resident individual and HUF buyers for this purpose.
- Seller documentation is now critical. Schedule E requires the seller’s foreign address, contact number, email, TRC and TIN. If the seller has no PAN, TRC and TIN are needed to avoid the higher rate. These should be collected well before the payment date.
- The relaxation is limited. Companies, firms and other non-individual buyers must continue to obtain a TAN and follow the regular procedure.
Where the NRI seller intends to repatriate the sale proceeds, TDS, capital gains computation, lower deduction certificates and FEMA/remittance compliance (Form 145/Form 146) should ideally be planned together from the outset. This avoids excess withholding, refund delays and hold-ups at the bank.
TDS on Purchase of Property from NRI: What Changes From 1 October 2026?
| Particulars | Up to 30 September 2026 | From 1 October 2026 |
|---|---|---|
| Seller | Non-resident | Non-resident |
| Buyer | Resident individual/HUF (no relaxation available) | Resident individual/HUF (relaxation applies) |
| Governing provision | Section 393(2) [Table: Sl. No. 17] | Section 393(2) [Table: Sl. No. 17] |
| TDS liability of buyer | Continues | Continues, no change |
| TAN of buyer | Mandatory | Not required |
| PAN of buyer | Required | Required, and used as the deductor’s identification |
| PAN of seller | Required; if not available, TDS at higher rate unless alternate details are furnished | Required; if not available, TRC and TIN must be furnished under rule 217 to avoid the higher rate |
| Monetary threshold | None. TDS applies on any amount | None. TDS applies on any amount |
| Rate of TDS | Rates in force, based on the nature of capital gain (LTCG/STCG), plus surcharge and cess. The flat 1% resident-seller rate does not apply | Same, no change |
| Lower/nil deduction certificate | Available under section 395(1)/(2) | Available under section 395(1)/(2), and certificates issued under section 395(6) by the prescribed authority are also recognised |
| Mode of deposit | TAN-based challan | PAN-based challan-cum-statement in Form No. 141 |
| Reporting | Regular quarterly TDS statement for non-residents | New Schedule E of Form No. 141, filed transaction-wise |
| Seller details to be reported | As per regular TDS statement | Foreign address, contact number and email (mandatory even if PAN is available), TRC number, TIN, status code and share in consideration |
| Instalment payments | Covered in quarterly statements | First, subsequent or last instalment to be indicated, with earlier acknowledgement numbers linked |
| Joint buyers | Each buyer needs a TAN | Each buyer files a separate Form 141 under their own PAN |
| Company, firm or other buyers | TAN required | TAN required. The relaxation does not apply to them |
- “Buyer covered by relaxation” (up to 30 September). No relaxation existed before 1 October, so that column now says so.
- ₹50 lakh threshold. Your draft read “Not applicable in the same manner / Same.” Both periods now say plainly that there is no threshold and TDS applies on any amount.
- 1% resident rate. Folded into the “Rate of TDS” row so the actual basis of the rate is visible.
- Section 395(6). Added in the lower-deduction row, since this notification expressly recognises certificates under it.
Key Takeaway: TDS on Purchase of Property from an NRI
From 1 October 2026, resident individuals and HUFs purchasing property from NRIs will benefit from a simpler PAN-based TDS compliance framework, removing the need for a TAN while retaining all substantive TDS obligations.
- TAN requirement before and after 1 October 2026 Until 30 September 2026, a resident individual or HUF purchasing property from an NRI must obtain a TAN, deposit TDS through the TAN-based system, and report the deduction in Form 144. From 1 October 2026, such buyers can use their PAN to deduct and deposit TDS through Form 141 (Schedule E), eliminating the need for a TAN. However, companies, firms, and other non-individual buyers must continue to obtain and use a TAN.
- TDS rate and threshold remain unchanged The amendment simplifies the compliance process but does not change the tax liability. The ₹50 lakh threshold applicable to resident sellers does not apply to NRI sellers, and TDS is not a flat 1%. Tax must be deducted at the applicable rate based on the nature of the capital gain, along with surcharge and cess. Eligible NRIs may obtain a lower or nil deduction certificate under section 395 to reduce excess TDS.
- Transactions spanning September and October 2026 For transactions that cross the implementation date, the applicable procedure depends on the date of payment or credit, not the registration date. Payments made up to 30 September 2026 must follow the existing TAN-based system, while payments made on or after 1 October 2026 can follow the new PAN-based mechanism.
- Repatriation of sale proceeds NRIs can remit property sale proceeds outside India subject to compliance with tax laws, FEMA regulations, and banking requirements. Banks may require proof of TDS payment and related remittance documentation. Therefore, TDS compliance, capital gains taxation, lower deduction certificates, and repatriation planning should be considered together at the beginning of the transaction.
For end-to-end support on NRI property transactions, including TDS computation, lower deduction certificates, capital gains and FEMA repatriation compliance, contact IFCCL, P-6/90 (2F), Connaught Circus, Connaught Place, New Delhi-110001 | +011-43-52-0194 | +91-98-11-322-785 | info@caindelhiindia.com | www.caindelhiindia.com
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.