Filing ITR in Response to a Section 148 Notice: Action Plan
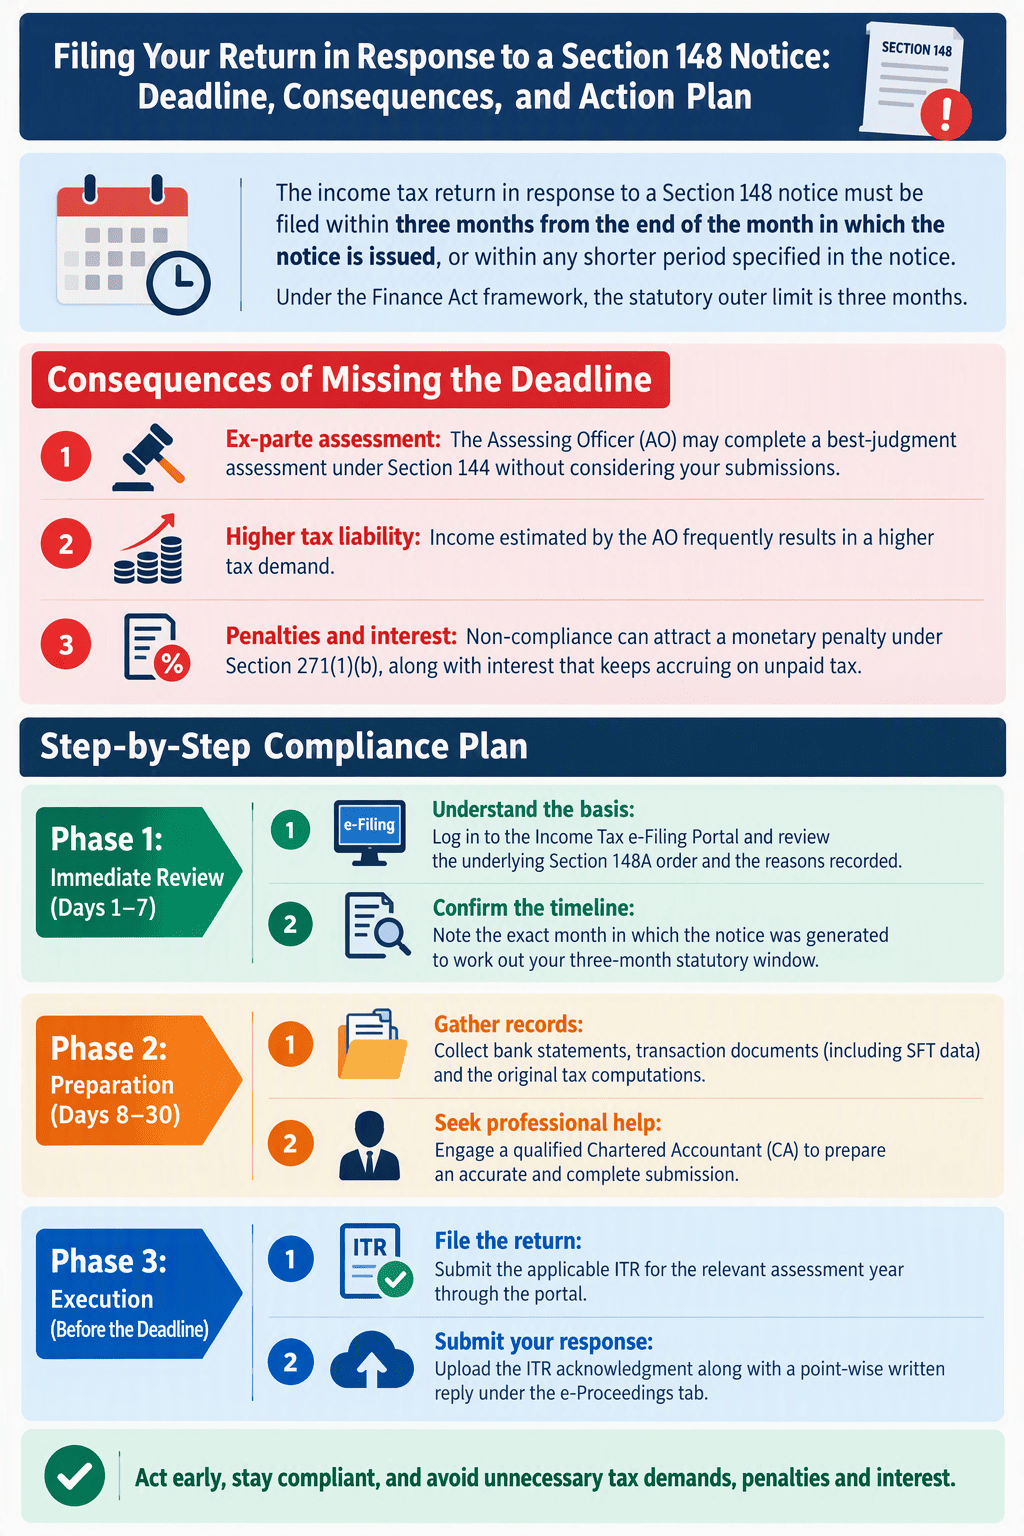
Table of Contents
Filing ITR in Response to a Section 148 Notice: Deadline & Action Plan
The income tax return in response to a Section 148 notice must be filed within three months from the end of the month in which the notice is issued, or within any shorter period specified in the notice. Under the Finance Act framework, the statutory outer limit is three months.
Don’t Miss the Deadline for Filing a Return in Response to a Section 148 Notice
The due date for filing a return in response to a notice u/s 148 is a critical compliance date and should never be overlooked.
- When a notice is issued u/s 148 of the Income-tax Act, the Assessing Officer specifies the period within which the assessee must furnish the return of income. This period is generally 90 days from the date of service of the notice (not exceeding three months from the end of the month in which the Section 148 notice is issued).
- Under the current provisions, a return filed pursuant to a Section 148 notice must be furnished within the time allowed in the notice. Missing this timeline can have serious procedural and legal consequences. In particular, a return filed after the prescribed period may not be treated as a return furnished u/s139. This could affect the assessee’s ability to raise or rely on certain statutory safeguards and procedural rights that depend on a valid return of income.
- Therefore, on receiving a Section 148 notice, the assessee should carefully note the deadline and ensure the return is filed within the stipulated time. The time limit should not be treated as merely procedural or directory. Any delay may have a knock-on effect in the subsequent reassessment proceedings, including issues relating to the issue and validity of a notice u/s 143(2).
- For notices issued u/s 148 of the Income-tax Act, 1961 at the end of June 2026, the time allowed for filing the return of income would expire around the end of September 2026. This statutory timeline should be kept firmly in mind while taking the necessary steps in the reassessment proceedings.
Filing Your Return in Response to a Section 148 Notice: Deadline, Consequences, and Action Plan
The income tax return in response to a Section 148 notice must be filed within three months from the end of the month in which the notice is issued, or within any shorter period specified in the notice. Under the Finance Act framework, the statutory outer limit is three months.
Consequences of Missing the Deadline
- Ex-parte assessment: The Assessing Officer (AO) may complete a best-judgment assessment under Section 144 without considering your submissions.
- Higher tax liability: Income estimated by the AO frequently results in a higher tax demand.
- Penalties and interest: Non-compliance can attract a monetary penalty under Section 271(1)(b), along with interest that keeps accruing on unpaid tax.
Step-by-Step Compliance Plan
Phase 1: Immediate Review (Days 1–7)
- Understand the basis: Log in to the Income Tax e-Filing Portal and review the underlying Section 148A order and the reasons recorded.
- Confirm the timeline: Note the exact month in which the notice was generated to work out your three-month statutory window.
Phase 2: Preparation (Days 8–30)
- Gather records: Collect bank statements, transaction documents (including SFT data) and the original tax computations.
- Seek professional help: Engage a qualified Chartered Accountant (CA) to prepare an accurate and complete submission.
Phase 3: Execution (Before the Deadline)
- File the return: Submit the applicable ITR for the relevant assessment year through the portal.
- Submit your response: Upload the ITR acknowledgment along with a point-wise written reply under the e-Proceedings tab.
A quick suggestion before publishing: it may be worth re-checking the penalty reference (Section 271(1)(b)) and the “shorter period / Finance Act” wording against the current provisions, and aligning the timeline with your earlier post, which described the period as generally 90 days from service of notice. With the Income-tax Act, 2025 in force from 1 April 2026, you may also want to confirm whether the section numbers should reflect the new Act for notices issued after that date.
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.