SSE Registration, ZCZP Fund Raising, Disclosure for NPO
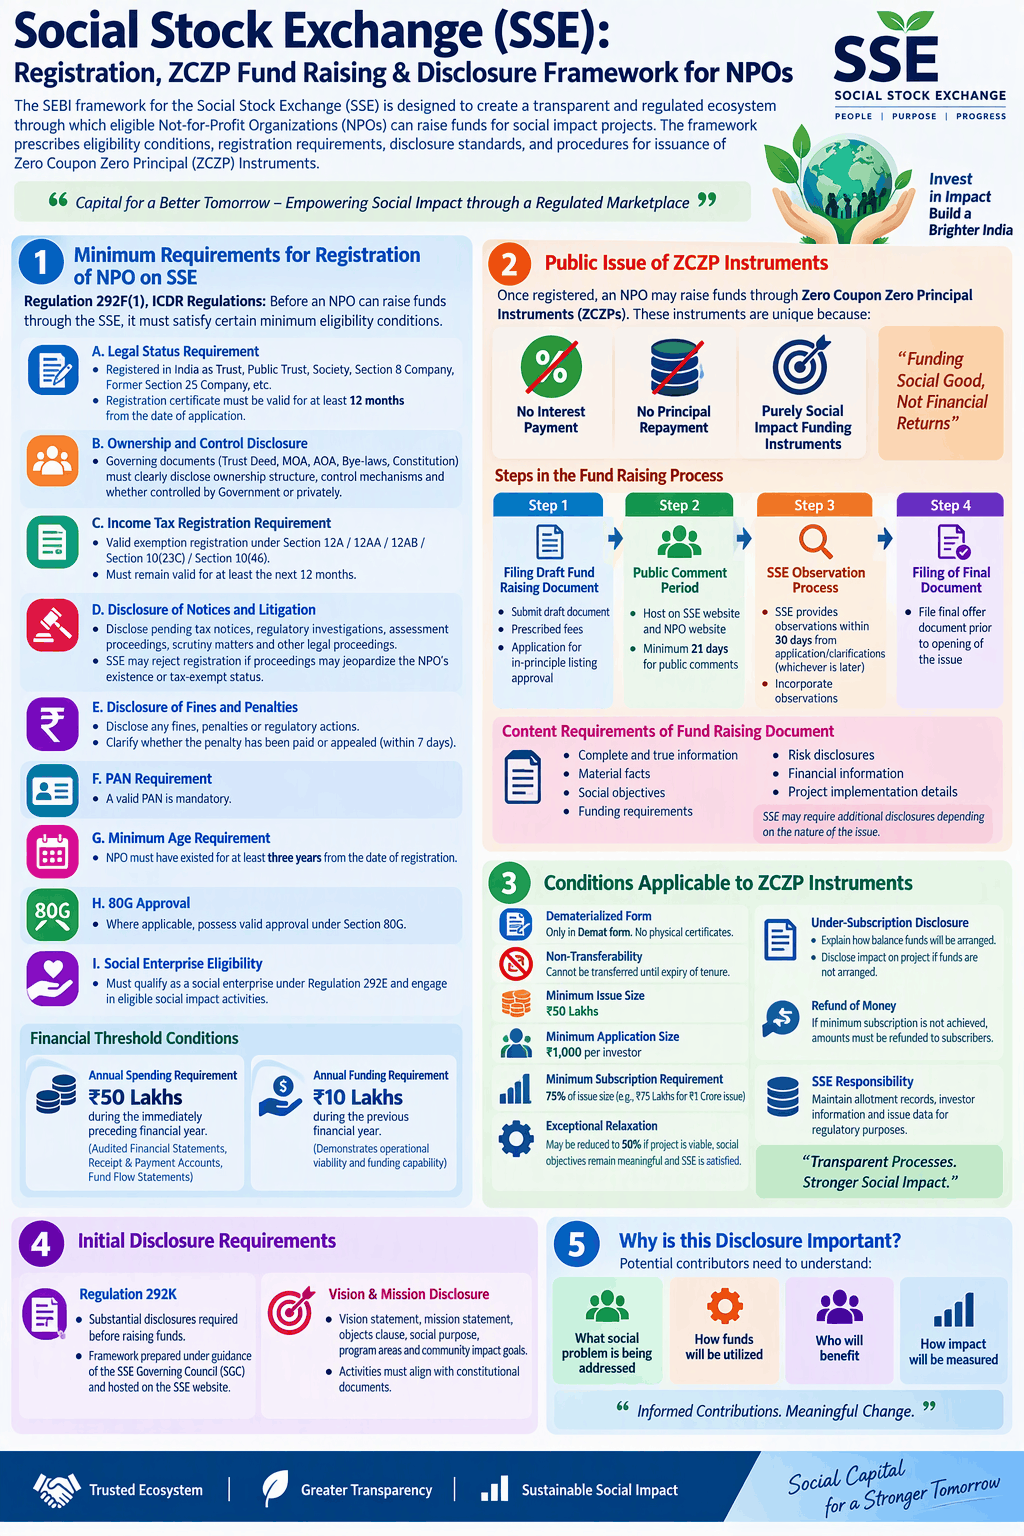
Table of Contents
Social Stock Exchange (SSE): Registration, ZCZP Fund Raising & Disclosure Framework for NPOs
The SEBI framework for the Social Stock Exchange (SSE) is designed to create a transparent and regulated ecosystem through which eligible Not-for-Profit Organisations (NPOs) can raise funds for social impact projects. The framework prescribes eligibility conditions, registration requirements, disclosure standards, and procedures for issuance of Zero Coupon Zero Principal (ZCZP) Instruments.
-
Minimum Requirements for Registration of NPO on SSE
Regulation 292F(1), ICDR Regulations : Before an NPO can raise funds through the SSE, it must satisfy certain minimum eligibility conditions.
-
Legal Status Requirement
The organization must be registered in India as one of the following Trust under the Indian Trusts Act, 1882, Public Trust under State Trust Laws, Trust registered under the Registration Act, 1908, Society under the Societies Registration Act, 1860, Society under State Societies Registration Laws, Section 8 Company under the Companies Act, 2013, former section 25 Company under Companies Act, 1956.
Further, the registration certificate must remain valid for at least 12 months from the date of SSE registration application.
-
Ownership and Control Disclosure
The governing documents such as Trust Deed, Memorandum of Association (MOA), Articles of Association (AOA), Bye-laws, Constitution must clearly disclose Ownership structure, Control mechanisms, Whether controlled by Government, Whether controlled privately. This ensures transparency for investors and donors.
-
Income Tax Registration Requirement
The NPO must possess a valid exemption registration under any of the following Section 12A, Section 12AA, Section 12AB, Section 10(23C), Section 10(46). The registration must remain valid for at least the succeeding 12 months.
-
Disclosure of Notices and Litigation
The NPO must disclose pending notices from tax authorities, regulatory investigations, assessment proceedings, scrutiny matters and other legal proceedings. at the time of registration. Stock Exchanges may reject registration if the pending proceedings are serious enough to jeopardize the NPO’s existence or tax-exempt status.
-
Disclosure of Fines and Penalties
Any fines, penalties, or regulatory actions must be disclosed. The applicant must clarify whether: The penalty has been paid, or The order has been appealed within seven days of such action.
-
- PAN Requirement: A valid PAN is mandatory.
- Minimum Age Requirement: The NPO must have existed for at least three years from the date of registration, evidenced by valid registration documents.
-
- 80G Approval: Where applicable, the NPO should possess valid approval under Section 80G. This is important because donors and investors may obtain tax benefits for contributions made to qualifying entities.
-
- Social Enterprise Eligibility: The NPO must qualify as a social enterprise under Regulation 292E and engage in eligible social impact activities.
Financial Threshold Conditions
-
- Annual Spending Requirement The NPO must have incurred spending of at least INR 50 lakhs during the immediately preceding financial year. This is evidenced through audited financial statements, Receipt and payment accounts, and fund flow statements.
- Annual Funding Requirement: The NPO must have received at least INR 10 Lakhs during the previous financial year. This demonstrates operational viability and funding capability.
-
Public Issue of ZCZP Instruments :
Once registered, an NPO may raise funds through Zero Coupon Zero Principal Instruments (ZCZPs). These instruments are unique because No Interest Payment, No Principal Repayment, Purely Social Impact Funding Instruments
-
- Step 1: Filing Draft Fund Raising Document : The NPO must submit Draft Fund Raising Document, Prescribed Fees, Application for In-Principle Listing Approval to the SSE where it is registered.
- Step 2: Public Comment Period : The draft document must be hosted on SSE Website, NPO Website for at least 21 Days to allow public comments. This is similar to public consultation mechanisms followed in securities regulation.
- Step 3: SSE Observation Process : SSE provides observations within 30 Days from Date of Application, or Receipt of Clarifications sought by SSE whichever is later. The NPO must incorporate these observations before proceeding further.
- Step 4: Filing of Final Fund Raising Document : After incorporating SSE observations, the NPO files the final offer document prior to the opening of the issue.
Content Requirements of Fund Raising Document
The disclosure document must contain complete and true information, material facts, social objectives, funding requirements, risk disclosures, financial information, and project implementation details. The purpose is to enable informed decision-making by contributors. SSE may require additional disclosures depending on the nature of the issue.
Conditions Applicable to ZCZP Instruments
- Dematerialised Form: All ZCZP Instruments must be issued only in Demat Form No physical certificates are permitted.
- Non-Transferability: The instrument cannot be transferred from the original subscriber until expiry of its tenure. This ensures commitment toward the social objective.
- Minimum Issue Size: Minimum issue size INR 50 Lakhs
- Minimum Application Size : Minimum subscription by an investor of INR 1,000. This promotes broad-based participation.
- Minimum Subscription Requirement: Normally 75% minimum subscription must be achieved. Example: Issue Size = INR 1 Crore. Minimum Subscription Required = INR 75 Lakhs
- Exceptional Relaxation : Subscription may be reduced to 50% if Project remains financially viable, Social objectives remain meaningful and SSE is satisfied after due diligence.
- Under-Subscription Disclosure: The offer document must explain:
- How Balance Funds Will Be Arranged: if the minimum target is not achieved.
- Impact on Project if balance funds cannot be arranged, If minimum subscription levels are not achieved:
- Money Must Be Refunded : to Subscribers.
- SSE Responsibility: The SSE is responsible for maintaining allotment records, investor information and Issue Data for regulatory purposes.
Initial Disclosure Requirements
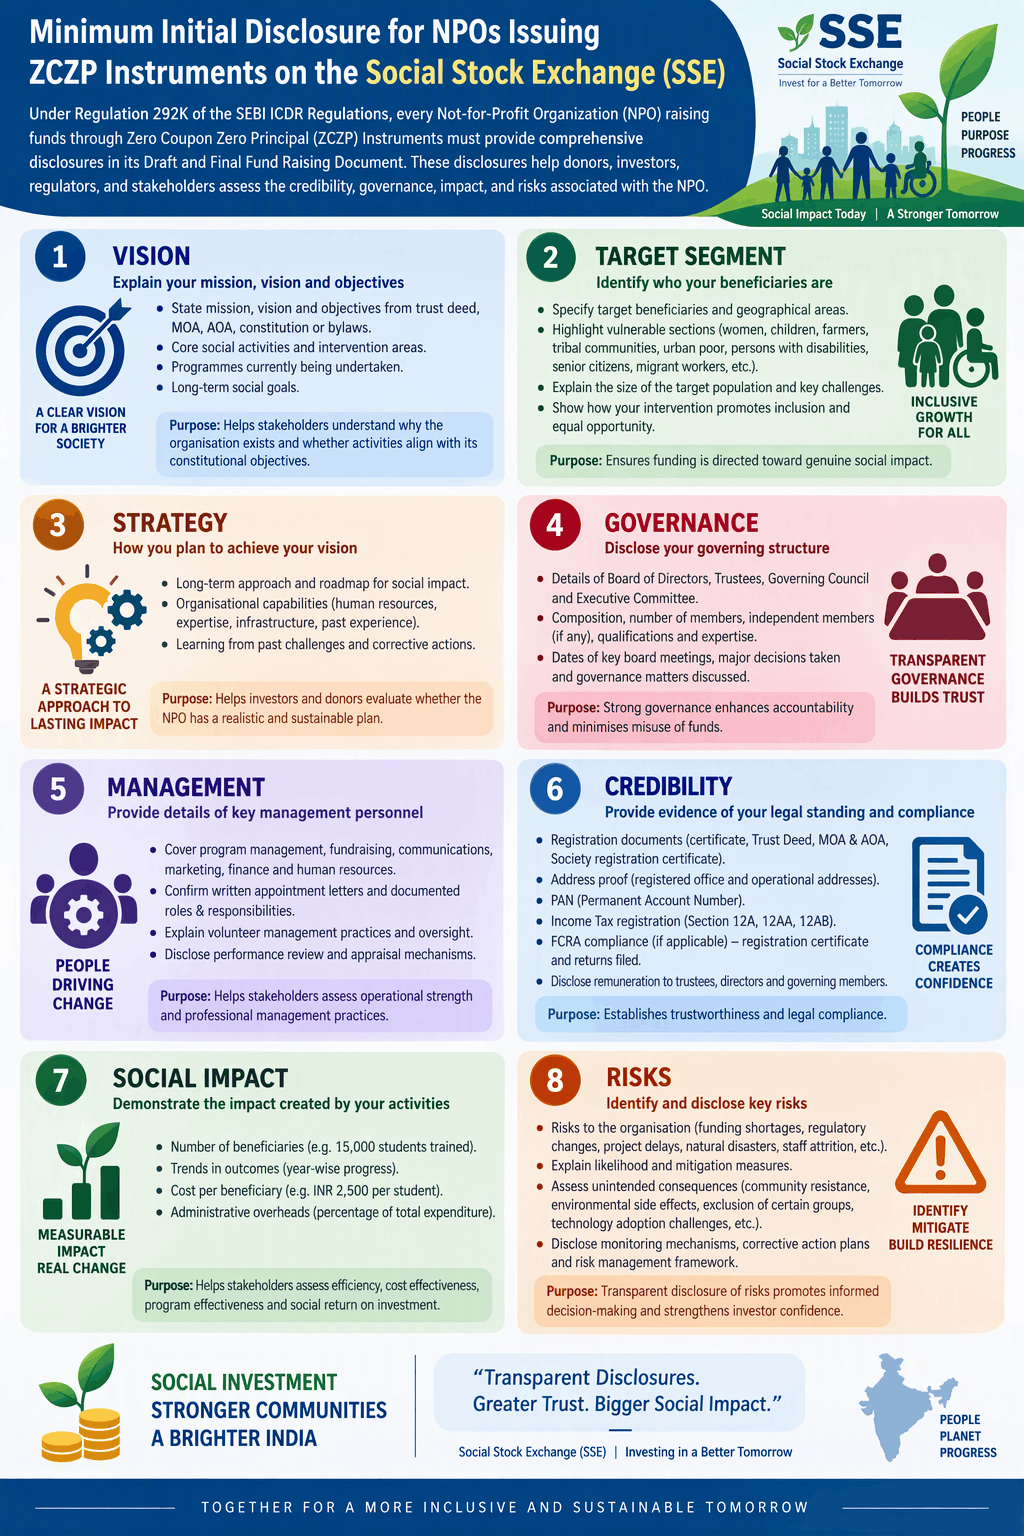
- Regulation 292K : Before raising funds, substantial disclosures are required. The disclosure framework is prepared under guidance of the SSE Governing Council (SGC) and hosted on the SSE website.
- Vision & Mission Disclosure : The NPO must clearly disclose Vision Statement, Mission Statement, Objects Clause, Social Purpose, Program Areas and Community Impact Goals. The disclosed activities must align with the constitutional documents of the organization.
Why is this Disclosure Important?
Potential contributors need to understand What social problem is being addressed? How funds will be utilized, Who will benefit, How impact will be measured. The SSE framework therefore follows a disclosure-based model similar to capital markets but focuses on social impact rather than financial returns.
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.