MCA Extends ROC Filing Due Dates for FY 2025-26
Table of Contents
MCA Extends ROC Filing Due Dates for FY 2025-26: Detailed Analysis
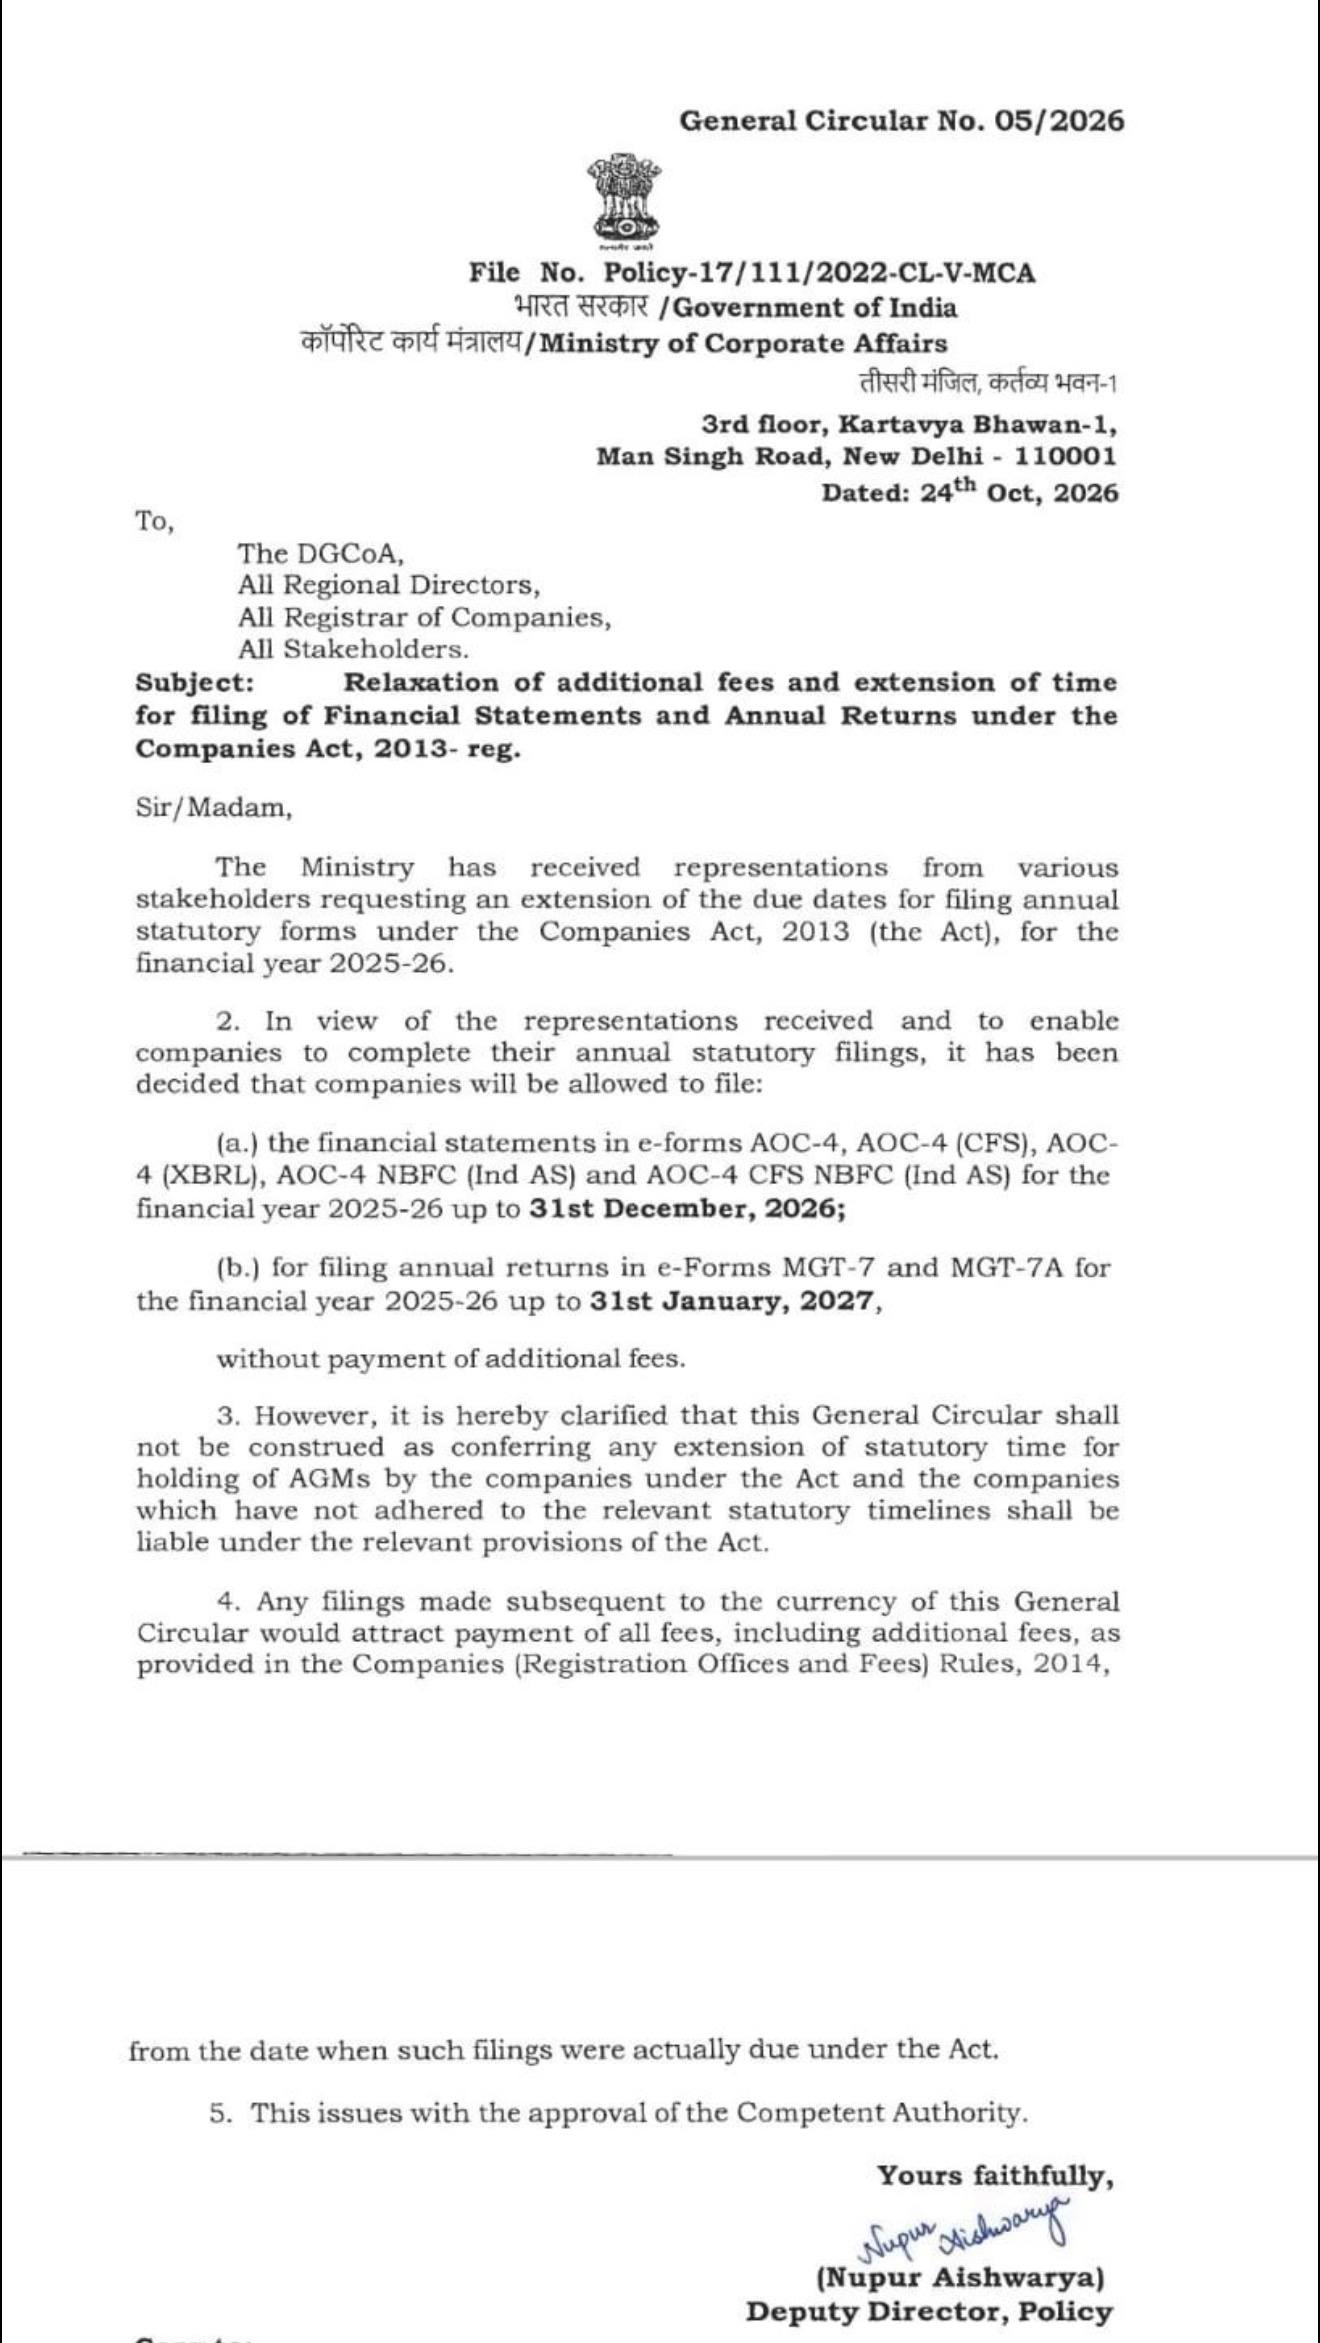
The Ministry of Corporate Affairs (MCA), through General Circular No. 05/2026 dated 24 October 2026, has granted significant relief to companies by extending the period for filing Financial Statements and Annual Returns for FY 2025-26 without payment of additional fees. This relaxation was provided in response to representations received from stakeholders seeking additional time for completing annual compliances.
What Has MCA Extended?
1. Extension for Filing Financial Statements:
- Companies can file the following forms relating to FY 2025-26 up to 31 December 2026 without payment of additional fees Form AOC-4, Form AOC-4 (CFS), Form AOC-4 (XBRL), Form AOC-4 NBFC (Ind AS) and Form AOC-4 CFS NBFC (Ind AS)
2. Extension for Filing Annual Returns
- Companies can file the following forms relating to FY 2025-26 up to 31 January 2027 without payment of additional fees Form MGT-7, Form MGT-7A
Meaning of the Extension:
Normally: Financial Statements (AOC-4) : Under Section 137 of the Companies Act, 2013, Form AOC-4 is required to be filed within 30 days of the AGM. For companies holding AGM on 30 September 2026, the normal due date would generally be 30 October 2026. Now, MCA has allowed filing up to 31 December 2026 without additional fees.
Annual Return (MGT-7/MGT-7A)
- Under Section 92 of the Companies Act, 2013, Annual Return is required to be filed within 60 days from the AGM.
- For companies holding AGM on 30 September 2026, the normal due date would generally be 29 November 2026.
- Now, MCA has allowed filing up to 31 January 2027 without additional fees.
Important Clarification: AGM Due Date Not Extended
- One of the most critical points in the circular is that MCA has NOT extended the due date for holding the Annual General Meeting (AGM). This means Companies must still hold their AGM within the statutory timelines prescribed under the Companies Act, 2013. The circular should not be interpreted as an extension of AGM due dates. Therefore, if a company fails to hold its AGM on time, the company and its officers may still be liable under the applicable provisions of the Companies Act.
No Additional Fees Till Extended Date
A major benefit of this circular is the waiver of additional filing fees. If companies file:
- By 31 December 2026: AOC-4, AOC-4 (CFS), and AOC-4 XBRL and related forms: No additional filing fees will be charged.
- By 31 January 2027: MGT-7, MGT-7A: No additional filing fees will be charged.
What If Filing Is Done After the Extended Date?
The circular clearly states that filings made after the relaxation period will attract Normal filing fees, Additional filing fees and Other applicable fees under the Companies (Registration Offices and Fees) Rules, 2014. Importantly, the calculation of additional fees may be reckoned from the original statutory due date and not from the extended date. Therefore, companies should not treat this as an indefinite extension.
Impact on Companies
- Relief for Audit Completion: Many companies face delays in the completion of statutory audits, finalization of accounts, consolidation of financial statements, and XBRL reporting The extension provides additional time to complete these activities properly.
- Ease of Annual Compliance: The relaxation helps private limited companies, public companies, NBFCs, Group Companies preparing CFS and to complete ROC compliances without the burden of additional fees.
- Reduced Compliance Pressure: Professionals such as chartered accountants, company secretaries, and corporate compliance teams receive additional time for annual filing activities during the busy audit and tax season.
Compliance Calendar After MCA Relaxation
| ROC Form | Purpose | Extended Due Date |
|---|---|---|
| AOC-4 | Financial Statements | 31 December 2026 |
| AOC-4 (CFS) | Consolidated Financial Statements | 31 December 2026 |
| AOC-4 XBRL | XBRL Filing | 31 December 2026 |
| MGT-7 | Annual Return | 31 January 2027 |
| MGT-7A | Annual Return (Small Companies/OPC) | 31 January 2027 |
Key Takeaways
- MCA has extended ROC filing timelines for FY 2025-26.
- AOC-4 and related financial statement forms can be filed up to 31 December 2026 without additional fees.
- MGT-7 and MGT-7A can be filed up to 31 January 2027 without additional fees.
- The extension is only for ROC filings and not for holding AGM.
- Companies failing to hold AGM within the prescribed time may still face legal consequences.
- Filings after the relaxation period will attract additional fees under the Companies Act framework.
Conclusion
The MCA’s relaxation is a welcome compliance relief for companies and professionals. While the extension provides extra time for filing annual forms, companies should remember that it is a waiver of additional fees for ROC filings and not an extension of statutory AGM timelines. Businesses should utilize this opportunity to ensure accurate financial reporting, proper audit completion, and timely ROC compliance to avoid future penalties and litigation risks.
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.