GST Registration for Scrap Dealers
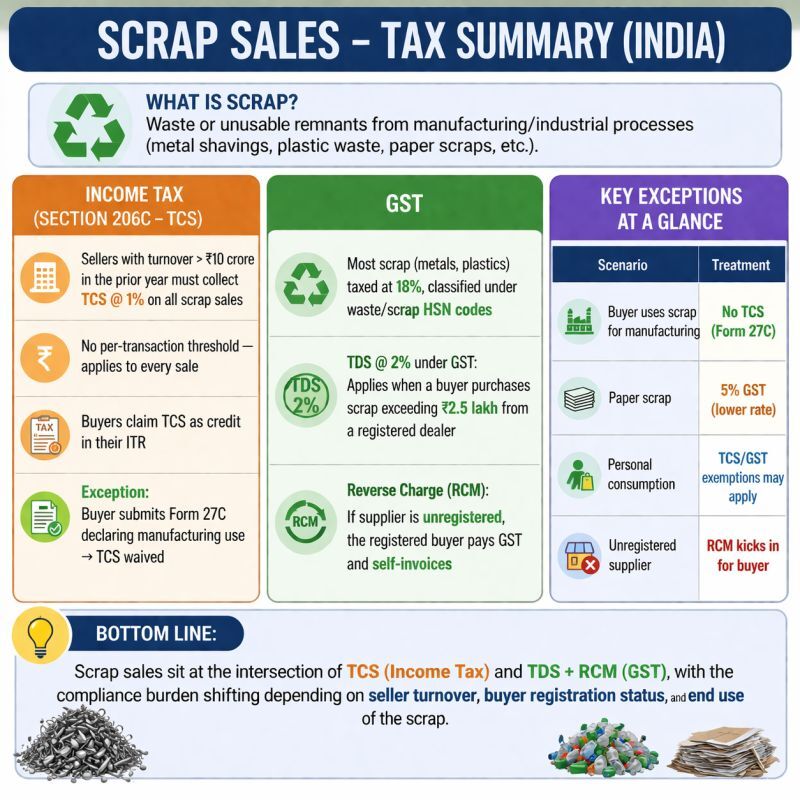
Table of Contents
GST Registration for Scrap Dealers
Background
Recent GST amendments have significantly changed the compliance framework applicable to scrap dealers. Earlier, businesses engaged exclusively in reverse charge supplies of metal scrap were generally exempt from GST registration under Notification No. 5/2017-Central Tax. However, with the implementation of Reverse Charge Mechanism (RCM) on various categories of scrap and waste products, taxpayers must carefully evaluate their registration requirements and GST liability.
The Government has expanded the RCM framework beyond metal scrap and, effective from 1 November 2026, has included additional categories such as Used Cooking Oil, Plastic Scrap, E-Waste, and Tyre Waste & Scrap. Businesses dealing in such products should review their GST registration position and compliance obligations.
Position Prior to Amendment
Under Section 23(2) of the CGST Act, the Government may exempt certain categories of persons from obtaining GST registration.
Accordingly, persons engaged exclusively in supplies liable to tax under Reverse Charge Mechanism (RCM) were exempted from GST registration under Notification No. 5/2017-Central Tax.
Position After Amendment
With the introduction of RCM on additional categories of scrap products, taxpayers dealing in the following items must examine the nature of their supplies:
- Used Cooking Oil
- Plastic Waste & Scrap
- E-Waste
- Tyre Waste & Scrap
- Metal Scrap
Where supplies are exclusively covered under RCM notification, GST registration may not be required.
However, where supplies are not exclusively covered under RCM, taxpayers must evaluate the aggregate turnover threshold and determine registration liability accordingly.
GST Registration Threshold
For suppliers dealing in goods:
- GST Registration Threshold Limit: INR 40 Lakhs Aggregate Turnover per Financial Year
- If the taxpayer supplies items not covered fully under RCM, normal registration provisions will apply.
Section 23(2) of the CGST Act empowers the Government to exempt specified persons from GST registration. Based on this power, Notification No. 5/2017 was issued for persons making only supplies taxable under RCM. Later amendments changed the treatment of scrap dealers. following key changes
- Metal Scrap RCM introduced from 10-Oct-2024 through Notification 24/2024.
- New categories added from 01-Nov-2026 through Notification 6/2026: Used Cooking Oil, Plastic Waste & Scrap, E-Waste and Tyre Waste & Scrap
Registration Impact
Case A: Dealer deals ONLY in specified RCM scrap items
If the dealer supplies only the notified scrap items on which GST is payable under RCM, registration exemption may continue to apply, subject to satisfaction of conditions under the notification.
Case B: Dealer deals in RCM items + other normal taxable goods
Registration threshold must be checked. GST registration becomes mandatory once turnover exceeds the threshold.
Turnover Threshold: For goods, the threshold mentioned in the document is ₹40 lakh aggregate turnover in a financial year.
GST Liability Matrix for Scrap Transactions
The document explains GST treatment based on seller and buyer status.
| Supplier | Buyer | GST Applicability |
| Unregistered | Unregistered | No GST |
| Unregistered | Registered | RCM @ 18% |
| Registered | Unregistered | FCM @ applicable rate |
| Registered | Registered | FCM @ applicable rate |
Meaning of FCM
Forward Charge Mechanism Supplier Raises tax invoice, Collects GST, Deposits GST with Government and Reports in GSTR-1 and GSTR-3B
Meaning of RCM
Reverse Charge Mechanism : Recipient:
- Pays GST directly to Government
- Claims ITC subject to eligibility
- Supplier normally does not collect GST from buyer
GST TDS Applicability on Scrap Purchases
Where scrap is supplied by a registered supplier to specified registered recipients, GST-TDS provisions may become applicable. Under Section 51, GST-TDS provisions may apply. According to the chart Who deducts?
Recipient/Buyer. Rate
- IGST = 2%
- CGST = 1%
- SGST = 1%
Total = 2% GST-TDS.
- Time of Deduction: At the time of payment.
- Threshold: Contract value exceeds INR 250,000.
- Registration: GST-TDS registration required where applicable.
- Return: GSTR-7 to be filed by the 10th of the next month.
| Particulars | Details |
|---|---|
| Person liable to deduct TDS | Buyer / Recipient |
| TDS Rate | 2% (1% CGST + 1% SGST) or 2% IGST |
| Time of Deduction | At the time of payment |
| Threshold Limit | Contract value exceeding ₹2,50,000 |
| GST TDS Registration | Required |
| TDS Return | GSTR-7 |
| Due Date | 10th of Next Month |
Scrap Categories Covered Under RCM
The document divides scrap into notified and non-notified categories.
Used Cooking Oil (RCM from 01-Nov-2026)
Examples: Restaurant frying oil, Hotel used cooking oil, Catering used oil, Used vegetable oil and Biodiesel feedstock oil HSN: 151800.
Important Exception : Industrial lubricating oil and engine waste oil (HSN 271099) remain under FCM, not this RCM category.
Plastic Waste & Scrap (RCM from 01-Nov-2026)
Examples: PET bottle scrap, HDPE drum scrap, LDPE bag scrap, Broken toys. Broken buckets, PVC pipe scrap, PP woven bag scrap, Mixed packaging waste, ABS engineering plastic scrap,
GST Rate: 18%.
Exception Reusable plastic drums, crates and similar usable goods are treated as normal goods and remain under FCM.
Tyre Waste & Rubber Scrap (RCM from 01-Nov-2026)
Examples: Tyre cuttings, Shredded tyre scrap, Rubber granules, Tractor tyre dismantling scrap, Car tyre scrap andBus tyre scrap
GST Rate: 18%.
Not Covered : Usable tyres and retreaded tyres remain under FCM.
E-Waste (RCM from 01-Nov-2026)
Examples: Laptop scrap, Desktop scrap, PCB scrap. Motherboard scrap, Mobile scrap, Printer scrap, Scanner scrap, Refrigerator scrap, AC scrap. Inverter scrap, Battery scrap
GST Rate: 18%.
Not Covered : Old working products sold as functioning assets generally continue under FCM.
Metal Scrap (RCM from 10-Oct-2024)
Ferrous Metal Scrap
Examples: Iron scrap, Steel scrap, HMS (Heavy Melting Scrap), Cast iron scrap, Stainless steel scrap, Alloy steel scrap, Iron borings, Railway track scrap, Machinery sold as scrap
GST Rate: 18%.
Non-Ferrous Metal Scrap : Examples: Copper scrap, Brass scrap, Aluminium scrap, Lead scrap, Zinc scrap, Tin scrap, Nickel scrap and Tungsten scrap
GST Rate: generally 18%.
Scrap Categories NOT under RCM
The following continue under the normal forward charge mechanism (FCM).
Paper & Cardboard Scrap
Examples: Newspaper waste, Office paper waste, Corrugated box scrap, Kraft paper scrap
Generally taxed at 5%.
Glass Scrap : Examples: Broken bottles, Glass cullet
Generally 18%.
- Wood Waste : Examples: Sawdust, Broken pallets, Fuel wood waste and Rate to be verified.
- Textile Waste : Examples:Cotton waste, Yarn waste, Textile rags, Synthetic waste and Usually under FCM.
- Leather Waste : Waste leather and leather dust.
- Furniture Scrap : Damaged wooden furniture.
- Demolition Debris : Construction rubble and demolition waste.
Categories Remaining Under Forward Charge Mechanism (FCM)
The following scrap categories generally continue under normal GST provisions Paper Scrap, Newspaper Scrap, Cardboard Scrap, Glass Scrap, Textile Waste, Wooden Waste, Leather Waste, Construction Debris, Furniture Scrap
Practical Compliance Checklist for Scrap Dealers
If the client is a scrap dealer:
- Step-1 : Identify whether the item falls in Metal Scrap, Plastic Scrap, E-Waste, Tyre Scrap, Used Cooking Oil. These are the primary notified RCM categories.
- Step-2 : Verify HSN classification before applying GST. Several entries in the document itself are marked “Verify”.
- Step-3: Check whether the buyer is registered.
- Step-4: Determine whether RCM or FCM applies.
- Step-5: Check GST registration requirement based on turnover and nature of supplies.
- Step-6 : If supplying to Government departments or notified entities, examine GST-TDS applicability.
Important caution to be taken care of
- The document itself contains a note: “For information purposes, please verify.” Some HSN codes, effective dates and GST rates should be cross-checked with the latest notifications, especially the entries relating to Used Cooking Oil, Plastic Scrap, E-Waste and Tyre Scrap introduced from 01-Nov-2026.
- As a GST practitioner, I would recommend maintaining a separate master sheet classifying clients into Exclusive RCM scrap dealers, Mixed RCM + FCM scrap dealers, Paper/Glass/Textile scrap dealers and Government-supply scrap dealers (GST-TDS exposure), because registration, invoicing and return requirements differ significantly among these categories
- GST Treatment on Scrap Transactions
Supplier Buyer GST Treatment Unregistered Unregistered No GST Unregistered Registered RCM Applicable (where notified) Registered Registered FCM or RCM as prescribed Registered Unregistered Supplier pays GST under FCM
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.