Overview on ITPs as per New I Tax Act 2025
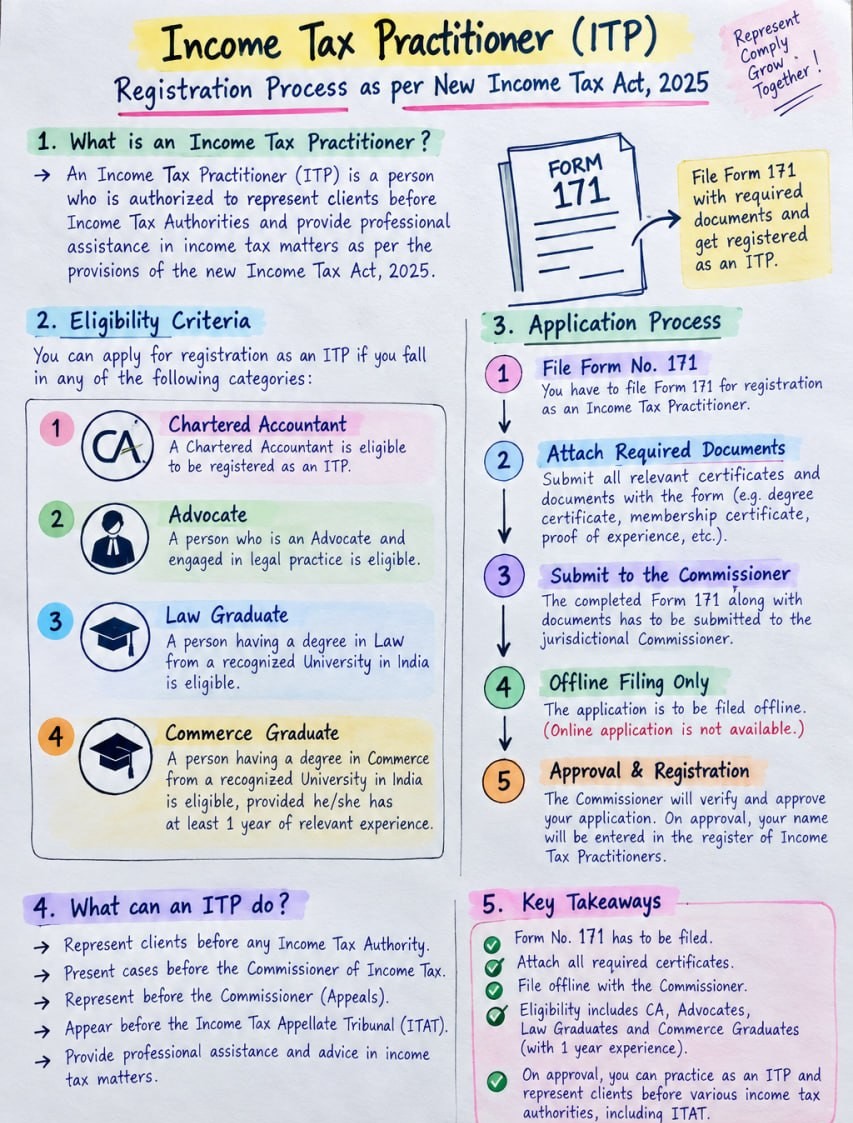
Table of Contents
Overview on Registration of Income-tax Practitioners (ITPs) as per New I Tax Act 2025
Section 515 of the Income-tax Act, 2025 – Authorised Income-tax Practitioners (ITPs)
Section 515 of the Income-tax Act, 2025 provides a formal framework for representation of taxpayers before Income-tax Authorities and the Appellate Tribunal through an authorised representative. This section is broadly similar to Section 288 of the Income-tax Act, 1961 but introduces a structured mechanism for recognition and registration of Authorised Income-tax Practitioners (ITPs)
Circular on Registration of Income-tax Practitioners (ITPs)
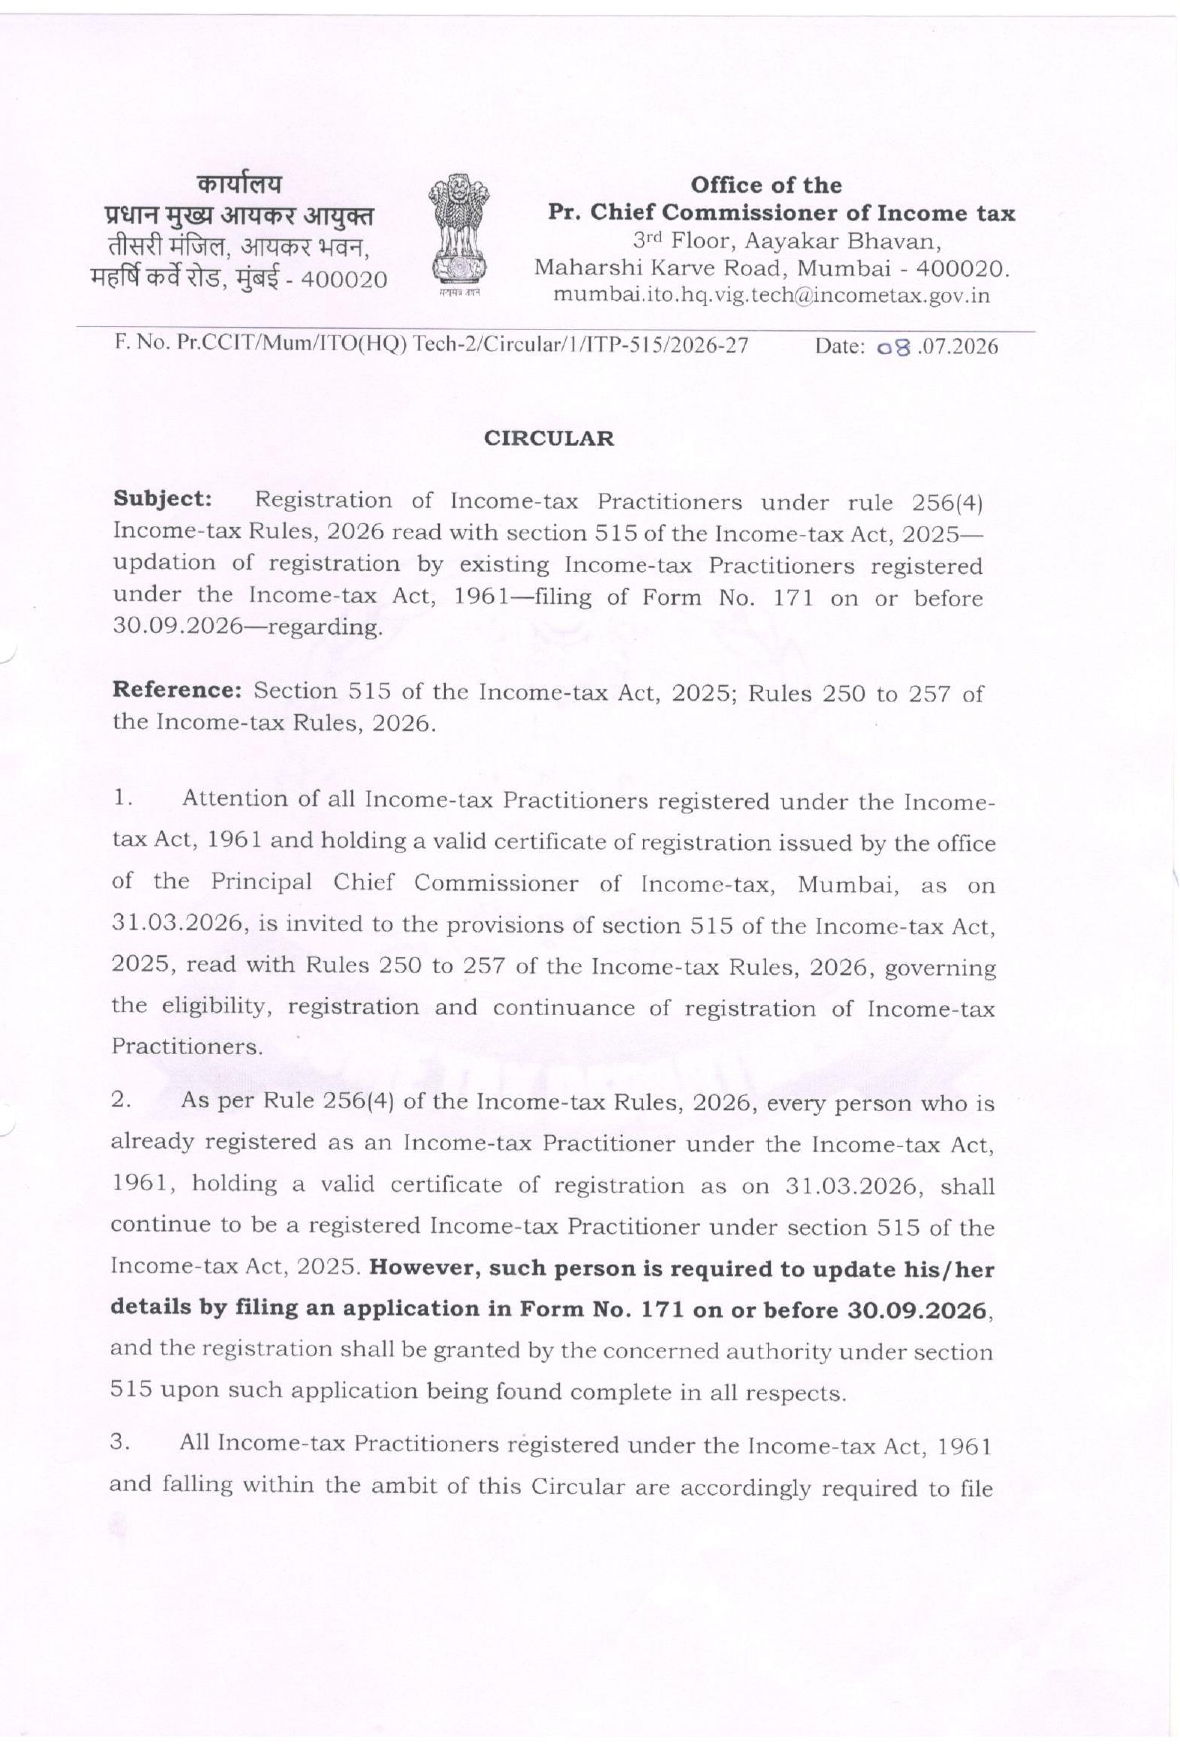
The circular has been issued by the Office of the Chief Principal Commissioner of Income Tax, Mumbai regarding the registration and continuation of registration of Income-tax Practitioners (ITPs) under the provisions of the Income-tax Act, 2025.
Basic Background of the CBDT Circular
New Income-tax Act, 2025, contains provisions relating to Income-tax practitioners under Section 515 read with Rules 250 to 257 of the Income-tax Rules, 2026. The circular specifically addresses individuals who were already registered as Income-tax practitioners under the earlier Income-tax Act, 1961 and whose registration was valid as on 31 March 2026.
Key Purpose of the CBDT Circular
Income Tax Department has invited all existing income-tax practitioners holding valid registration under the Income Tax Act, 1961 to migrate and continue their registration under the new Income Tax Act, 2025. The objective is to ensure that all practitioners are registered under the framework of the new law and are authorized to continue representing taxpayers before income-tax authorities.
Who is Covered ITP ?
The circular applies to:
- Income-tax Practitioners already registered under the Income-tax Act, 1961.
- Practitioners whose registration remained valid as on 31.03.2026.
- ITP Practitioners wishing to continue their practice under the Income-tax Act, 2025.
Requirement to File Form No. 171
CBDT circular states that eligible Income-tax practitioners are required to:
- Update their details.
- File an application in Form No. 171.
- Submit the application along with the prescribed supporting documents.
- Complete the filing process on or before 30 September 2026.
Place of Submission
Completed Form No. 171 and supporting documents must be submitted before the Principal Chief Commissioner of Income Tax, Mumbai. The introduction of Form 171 provides a regulated system for ITP who represent taxpayers before the Tax Dept. The provision aims to:
- Ensure only qualified persons represent assessees.
- Improve professional standards in tax practice.
- Maintain a formal register of authorised practitioners.
- Increase accountability and transparency in tax proceedings
Consequences of Non-Filing of Registered Income Tax Practitioners
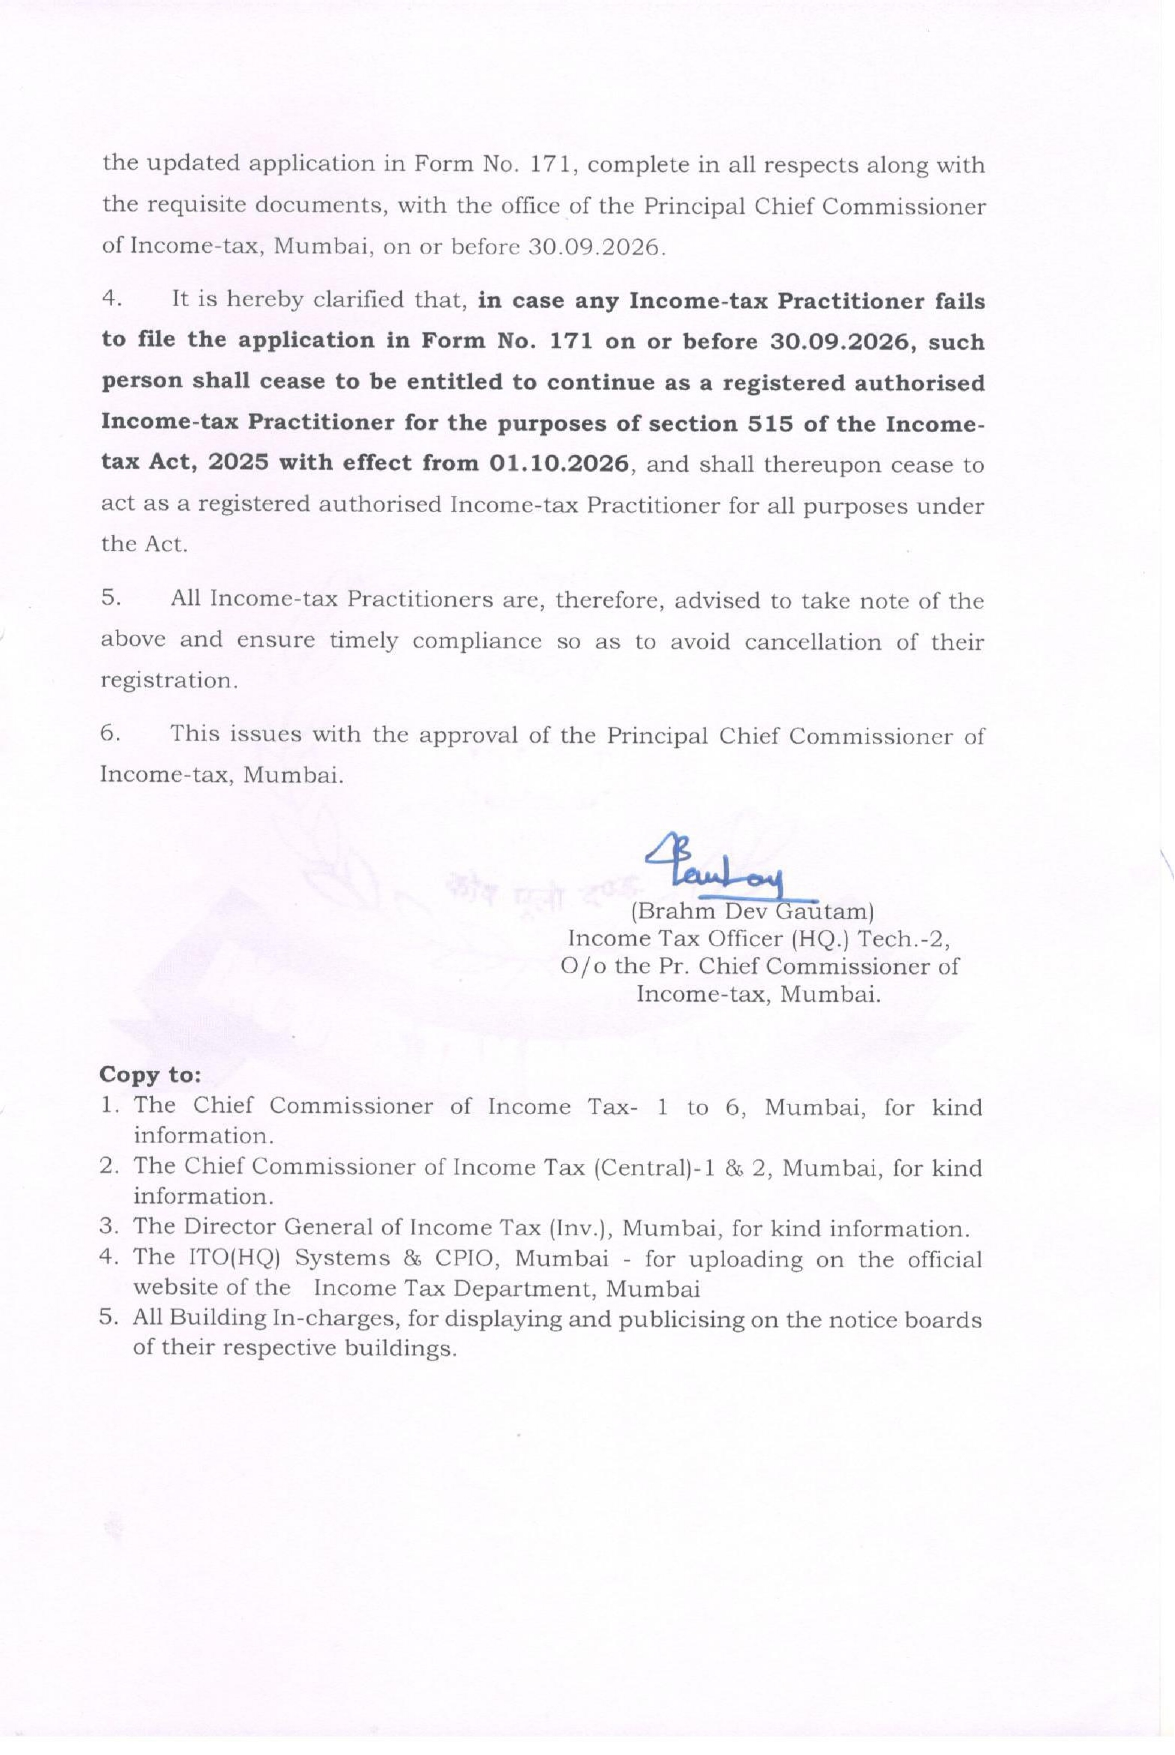
This CBDT circular contains an important warning. If an Income-tax practitioner fails to submit Form No. 171 on or before 30 September 2026, the practitioner:
- Will cease to be entitled to continue as a registered Income-tax practitioner.
- Who will not be considered an authorized Income-tax practitioner under the Income-tax Act, 2025.
- Will cease to act as a registered practitioner with effect from 01 October 2026.
In simple terms, failure to file the prescribed form by the due date will result in automatic discontinuation of the practitioner’s recognition under the new Income Tax Act.
Practical Impact of Existing Registered Income-Tax Practitioners
For existing registered income tax practitioners:
- Registration under the old law will not automatically continue under the new Income-tax Act, 2025.
- Fresh compliance through Form 171 is mandatory.
- Registration details must be updated and verified.
- Missing the deadline may result in loss of authority to represent taxpayers before Income-tax authorities.
A CA holding a valid COP is already covered within the definition of an AR u/s 515(3). But new provisions also allow other qualified professionals to obtain recognition via Registration in Form 171, thereby broadening the pool of recognised tax practitioners.
In summary
Section 515 of the Income-tax Act, 2025 establishes a formal legal framework for authorised representation before tax authorities, while Form 171 under the Income-tax Rules, 2026 creates a registration mechanism for recognised ITP, ensuring professionalism and regulatory oversight in tax representation.
CBDT Circular is essentially a migration and re-registration requirement for existing Income-tax practitioners. Any person who was registered as an ITP under the Income-tax Act, 1961 and wishes to continue practice under the Income-tax Act, 2025 must submit Form No. 171 along with supporting documents by 30 September 2026. Failure to do so will result in cessation of ITP status from 1 October 2026, thereby affecting the practitioner’s ability to represent clients before tax authorities
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.