GSTAT Simplify Procedure for Seeking Adjournment of Hearings
Table of Contents
GSTAT Pune Bench Circular No. 04/2026 – Procedure for Seeking Adjournment of Hearings
Goods and Services Tax Appellate Tribunal, Pune Bench, has issued detailed guidelines regarding the procedure for seeking adjournments in GST appeal matters. The objective is to ensure timely disposal of appeals, discourage unnecessary delays, and bring consistency in hearing management. The Goods and Services Tax Appellate Tribunal Pune Bench Circular issued by the Circular No. 4-2026 dated 21 October 2026 lays down a formal procedure for obtaining adjournments before the Goods and Services Tax Appellate Tribunal, Pune Bench. It aims to prevent unnecessary delays and ensure efficient disposal of GST appeals. Legal Basis
Existing Legal Framework:
The procedure for adjournment is governed by Section 113(2) of the CGST Act, 2017 and Rules 16 and 47 of the GSTAT (Procedure) Rules, 2025.
The circular is based on Section 113(2) of the CGST Act, 2017. The Appellate Tribunal may grant adjournment if sufficient cause is shown.
Under these provisions, an adjournment is not a matter of right and may be granted only when sufficient cause is demonstrated before the Tribunal. However No party can be granted more than three adjournments during the hearing of an appeal.
Goods and Services Tax Appellate Tribunal (Procedure) Rules, 2025
- Rule 16: Adjournments should normally be sought before the Bench.
- The Rule 47: Tribunal may adjourn proceedings on appropriate terms.
- Rule 42: Consequences of non-appearance of appellant.
- The Rule 43: Consequences of non-appearance of respondent.
Key Requirements for Seeking Adjournment
- Adjournment Can Be Granted Only by the Bench: The most important principle Merely filing an adjournment request does not automatically entitle a party to adjournment. Until the bench expressly grants the request, the matter remains fixed for hearing on the scheduled date.
- Normal Procedure: On the hearing date The party, its authorized representative, or another Authorized Representative on its behalf should appear before the Bench and seek adjournment. Exception: If an advance request has been filed as per the prescribed procedure, physical appearance is not mandatory and the Bench may decide the request based on documents.
- Advance Adjournment Request : When a party knows in advance that it cannot attend the hearing:
- Service on Opposite Party: The applicant must Send an advance copy to the opposite party or its AR. And Upload proof of such service along with the request. Proof may include Email delivery proof, Courier acknowledgement, Registered post receipt, Any other admissible evidence
Why Was This Circular Issued?
- The Goods and Services Tax Appellate Tribunal observed that parties were sending adjournment requests by email or letter directly to the Registry.
- Filing requests on the evening before or morning of the hearing. Not giving specific reasons. Not informing the opposite party.
- Remaining absent when the case was called and Seeking adjournments merely because the authorized representative was busy elsewhere or papers were not ready.
- These practices led to the wastage of judicial time, inconvenience to the opposite party and Delay in disposal of GST appeals.
Grounds Ordinarily Not Considered Sufficient:
The Tribunal has clarified that the following reasons may generally not justify adjournment Authorized Representative being engaged elsewhere, Last-minute change of counsel or AR, Papers not being ready, Failure to file documents within time and Internal administrative delays
- Grounds Normally Not Considered Sufficient: The Bench has specifically mentioned that the following reasons will ordinarily not justify adjournment:
- AR Busy Elsewhere: Counsel is engaged before another court or tribunal. Normally not acceptable.
- Last-Minute Change of Authorized Representative : Changing counsel immediately before the hearing is generally not a valid ground.
- Papers Not Ready : Lack of preparation or non-availability of documents is ordinarily not a sufficient cause.
- Non-Filing of Replies: Failure to file Reply, Rejoinder, Written Submissions, or Other Documents. within prescribed time limits shall generally not justify adjournment.
- Powers of the Bench : The Bench may grant adjournment or reject adjournment after recording reasons in writing.
Key Requirements for Seeking Adjournment
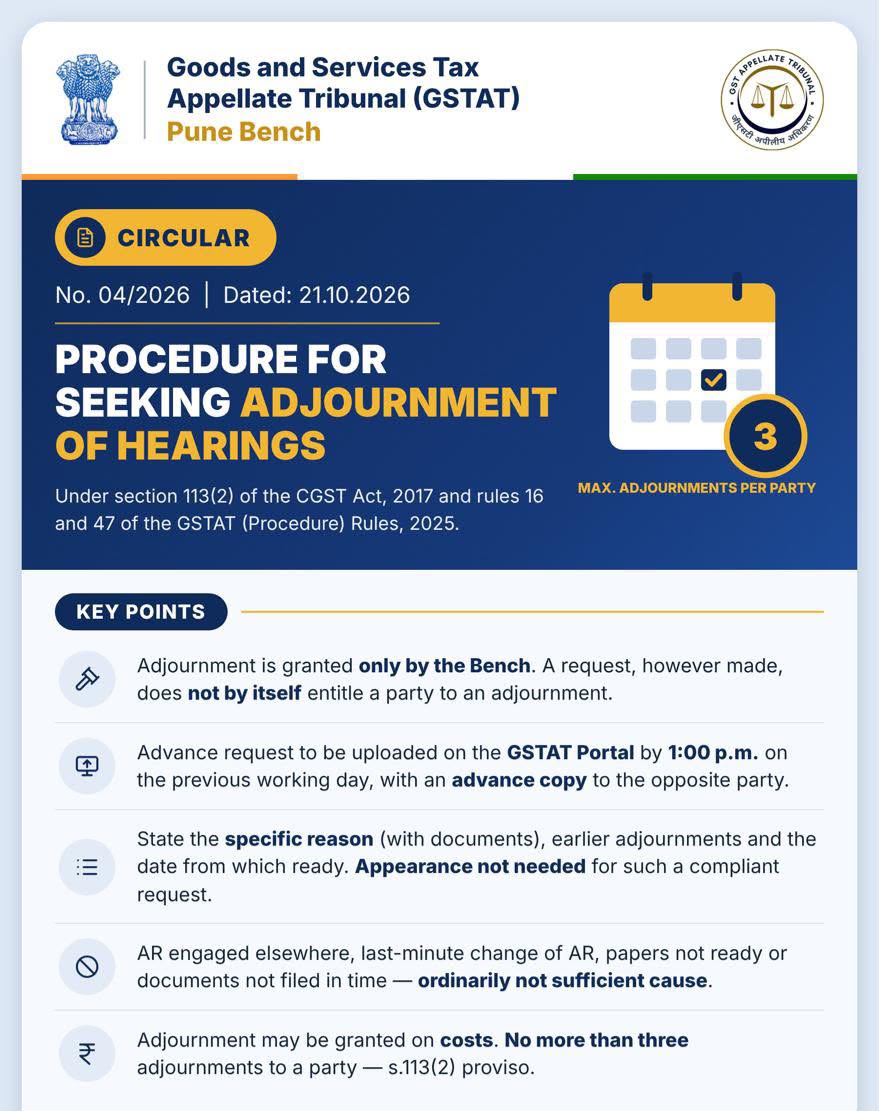
Taxpayers, authorized representatives, and departmental officers should note the following:
- Adjournment is Solely at the Discretion of the Bench : Merely filing an adjournment application does not automatically entitle a party to an adjournment. The request must be considered and approved by the concerned GSTAT Bench.
- Advance Filing Through GSTAT Portal: An adjournment request should be uploaded on the GSTAT Portal by 1:00 PM on the previous working day before the scheduled hearing date.
- Copy to Opposite Party: A copy of the adjournment application must be provided to the opposite party in advance, along with proof of service.
- Proper Justification Required: The application should clearly mention Specific reasons for seeking adjournment, Supporting documents, wherever applicable, Details of previous adjournments, if any, Expected date of readiness for hearing
- Appearance Not Required for a Compliant Request: Where a properly documented adjournment application is filed within the prescribed timeline, personal appearance may not be necessary solely for seeking adjournment.
Contents of Adjournment Application:
The application must contain:
-
- Basic Details: Appeal Number, Hearing Date, Name of Party and Name of Authorized Representative (AR)
- Specific Reason: The reason must be clearly stated. Where possible, supporting documents should be attached.Examples: Hospitalization, Serious illness, Medical emergency, natural calamity, death in immediate family, Evidence such as medical certificates should be enclosed.
- Previous Adjournments : The applicant must disclose Number of previous adjournments granted. Dates of those adjournments and Whether the same reason was cited earlier.
- Readiness Date : Where possible, mention From which date the party will be ready to proceed with hearing.
Consequences of Non-Appearance:
If Appellant Does Not Appear, the Bench may dismiss the appeal for default or Hear and decide the case on merits.
- If the Respondent Does Not Appear: The Bench may proceed expart and decide the appeal without the respondent’s participation.
- The Maximum Number of Adjournments: This is the most critical provision.
- Maximum: Three Adjournments Per Party : Once a party has received three adjournments: No further adjournment can be granted under Section 113(2) of the CGST Act. Example
| Adjournment No. | Allowed? |
| First | Yes |
| Second | Yes |
| Third | Yes |
| Fourth | Not Permissible |
- Exceptional Situations: The circular recognizes that emergencies may arise after the 1:00 PM cut-off. Examples: Sudden illness, medical emergency, accident, family bereavement, and Natural disaster. In such cases, a request may be filed after the deadline.
- The request may be uploaded before the hearing starts, and an advance copy should still be provided to the opposite party. The circular applies to all matters listed for hearing: On or after the 7th day from 21 October 2026. That is, effectively from 28 October 2026 onwards.
- Bench May Impose Costs: If adjournment is granted, the Bench may direct payment of costs to the opposite party. Example: If repeated adjournments cause unnecessary expense to the department or taxpayer, costs may be imposed as a condition for granting adjournment.
Key Benefits of the New Framework:
The revised procedure is expected to improve discipline in litigation proceedings. Reduce last-minute hearing disruptions, Encourage timely preparation of cases, Ensure faster disposal of GST appeals and Enhance overall efficiency of the GSTAT system
Practical Takeaway for Procedure for Seeking Adjournment of Hearings
- Businesses, tax consultants, Chartered Accountants, and advocates handling GST disputes should maintain complete documentation and plan hearings well in advance. As adjournments are no longer viewed as routine procedural requests, parties should be prepared to substantiate any request with genuine and documented reasons.
- File adjournment requests through the Goods and Services Tax Appellate Tribunal Portal only. Upload requests before 1:00 PM of the previous working day. Serve a copy on the opposite party and retain proof. Mention specific reasons with documentary evidence. Do not rely on grounds like “counsel busy elsewhere” or “papers not ready”. Track the number of adjournments already availed. Remember that adjournment is a discretion of the Bench, not a right.
- For GST litigants and professionals, this circular signals a stricter approach toward adjournments and emphasizes timely preparation and efficient disposal of appeals before the Goods and Services Tax Appellate Tribunal.
Conclusion
The GSTAT’s streamlined adjournment framework marks a significant step towards efficient and time-bound GST dispute resolution. Taxpayers should carefully adhere to the prescribed procedure and avoid relying on routine or avoidable grounds for adjournment. Proper preparation and timely compliance will play a crucial role in ensuring a smooth appellate process before the Tribunal.
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.