GST RATE SCHEDULE for SCRAP, WASTE & RESIDUE PRODUCTS
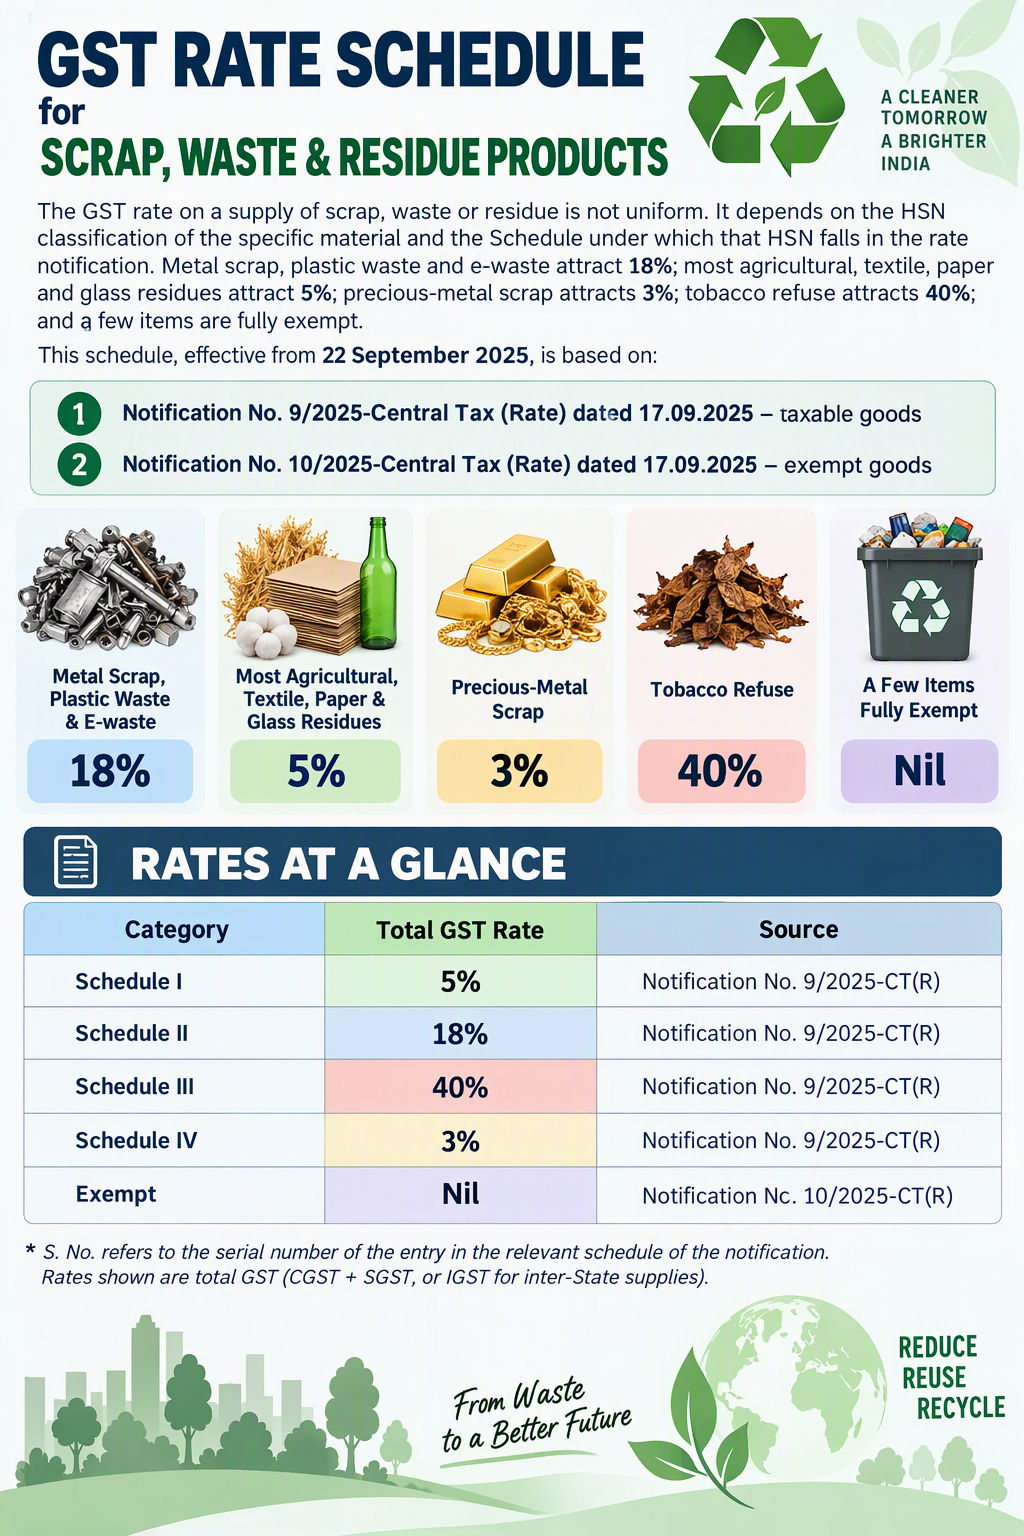
Table of Contents
GST RATE SCHEDULE for SCRAP, WASTE & RESIDUE PRODUCTS
The GST rate on a supply of scrap, waste or residue is not uniform. It depends on the HSN classification of the specific material and the Schedule under which that HSN falls in the rate notification. Metal scrap, plastic waste and e-waste attract 18%; most agricultural, textile, paper and glass residues attract 5%; precious-metal scrap attracts 3%; tobacco refuse attracts 40%; and a few items are fully exempt. This schedule, effective from 22 September 2025, is based on:
- Notification No. 9/2025-Central Tax (Rate) dated 17.09.2025 – taxable goods
- Notification No. 10/2025-Central Tax (Rate) dated 17.09.2025 – exempt goods
Rates at a Glance
| Category | Total GST Rate | Source |
| Schedule I | 5% | Notification No. 9/2025-CT(R) |
| Schedule II | 18% | Notification No. 9/2025-CT(R) |
| Schedule III | 40% | Notification No. 9/2025-CT(R) |
| Schedule IV | 3% | Notification No. 9/2025-CT(R) |
| Exempt | Nil | Notification No. 10/2025-CT(R) |
* S. No. refers to the serial number of the entry in the relevant schedule of the notification. Rates shown are total GST (CGST + SGST, or IGST for inter-State supplies).
Schedule I — Scrap, Waste & Residue Taxable at 5%
Total GST 5% (CGST 2.5% + SGST 2.5%) | Notification No. 9/2025-CT(Rate) dated 17.09.2025
| S. No.* | HSN Code | Description of Goods | GST Rate |
| 12 | 0502 | Pigs’, hogs’ or boars’ bristles and hair; badger hair and other brush-making hair; waste of such bristles or hair | 5% |
| 14 | 0505 | Skins and other parts of birds, with their feathers or down, feathers and parts of feathers (whether or not with trimmed edges) and down, not further worked than cleaned, disinfected or treated for preservation; powder and waste of feathers or parts of feathers | 5% |
| 15 | 0507 (except 050790) | Ivory, tortoise-shell, whalebone and whalebone hair, horns, unworked or simply prepared but not cut to shape; powder and waste of these products | 5% |
| 16 | 0508 | Coral and similar materials, unworked or simply prepared but not otherwise worked; shells of molluscs, crustaceans or echinoderms and cuttle-bone, unworked or simply prepared but not cut to shape; powder and waste thereof | 5% |
| 99 | 1522 | Degras; residues resulting from the treatment of fatty substances or animal or vegetable waxes | 5% |
| 112 | 1802 | Cocoa shells, husks, skins and other cocoa waste | 5% |
| 154 | 2302 | Bran, sharps and other residues, whether or not in the form of pellets, derived from the sifting, milling or other working of cereals or of leguminous plants [other than aquatic feed including shrimp feed and prawn feed, poultry feed and cattle feed, including grass, hay and straw, supplements and additives, husk of pulses including chilka, concentrates including chuni or churi, khanda, wheat bran, de-oiled cake] | 5% |
| 156 | 2303 | Residues of starch manufacture and similar residues, beet-pulp, bagasse and other waste of sugar manufacture, brewing or distilling dregs and waste, whether or not in the form of pellets | 5% |
| 157 | 2304 | Oil-cake and other solid residues, whether or not ground or in the form of pellets, resulting from the extraction of soya-bean oil | 5% |
| 158 | 2305 | Oil-cake and other solid residues, whether or not ground or in the form of pellets, resulting from the extraction of ground-nut oil | 5% |
| 159 | 2306 | Oil-cake and other solid residues, whether or not ground or in the form of pellets, resulting from the extraction of vegetable or microbial fats or oils, other than those of heading 2304 or 2305, other than cottonseed oil cake and de-oiled rice bran | 5% |
| 160 | 2307 | Wine lees; argol | 5% |
| 182 | 2517 | Pebbles, gravel, broken or crushed stone, of a kind commonly used for concrete aggregates, road metalling or railway or other ballast, shingle and flint, whether or not heat-treated; macadam of slag, dross or similar industrial waste, whether or not incorporating the materials cited in the first part of the heading; tarred macadam; granules, chippings and powder of stones of heading 2515 or 2516, whether or not heat-treated | 5% |
| 189 | 2525 | Mica, including splittings; mica waste | 5% |
| 201 | 2618 | Granulated slag (slag sand) from the manufacture of iron or steel | 5% |
| 202 | 2619 | Linz-Donawitz (LD) slag | 5% |
| 236 | 3006 | Pharmaceutical goods specified in Note 4 to Chapter 30, i.e. sterile surgical catgut, similar sterile suture materials (including sterile absorbable surgical or dental yarns) and sterile tissue adhesives for surgical wound closure; sterile laminaria and sterile laminaria tents; sterile absorbable surgical or dental haemostatics; sterile surgical or dental adhesion barriers, whether or not absorbable; waste pharmaceuticals (other than contraceptives); ostomy appliances including pouch or flange, stoma adhesive paste, barrier cream, irrigator kit, sleeves, belt, micro-pore tapes | 5% |
| 267 | 4004 00 00 | Waste, parings and scrap of rubber (other than hard rubber) | 5% |
| 277 | 4017 | Waste or scrap of hard rubber | 5% |
| 288 | 4115 | Composition leather with a basis of leather or leather fibre, in slabs, sheets or strip, whether or not in rolls; parings and other waste of leather or of composition leather, not suitable for the manufacture of leather articles; leather dust, powder and flour | 5% |
| 294 | 4401 | Wood in chips or particles; sawdust and wood waste and scrap, whether or not agglomerated in logs, briquettes, pellets or similar forms | 5% |
| 316 | 4706 | Pulps of fibres derived from recovered (waste and scrap) paper or paperboard or of other fibrous cellulosic material | 5% |
| 317 | 4707 | Recovered (waste and scrap) paper or paperboard | 5% |
| 326 | 5007 | Woven fabrics of silk or of silk waste | 5% |
| 331 | 5201 to 5203 | Cotton and cotton waste | 5% |
| 335 | 5301 | Flax, raw or processed but not spun; flax tow and waste (including yarn waste and garnetted stock) | 5% |
| 336 | 5302 | True hemp (Cannabis sativa L.), raw or processed but not spun; tow and waste of true hemp (including yarn waste and garnetted stock) | 5% |
| 337 | 5303 | Textile bast fibres (other than jute fibres), raw or processed but not spun; tow and waste of these fibres (including yarn waste and garnetted stock) | 5% |
| 345 | 5505 | Waste of man-made fibres | 5% |
| 391 | 6309 or 6310 | Worn clothing and other worn articles; rags | 5% |
| 406 | 7001 | Cullet and other waste and scrap of glass | 5% |
| 437 | 84, 85 or 94 | Renewable energy devices and parts for their manufacture: (a) bio-gas plant; (b) solar power-based devices; (c) solar power generator; (d) windmills, Wind Operated Electricity Generator (WOEG); (e) waste-to-energy plants/devices; (f) solar lantern/solar lamp; (g) ocean waves/tidal waves energy devices/plants; (h) photovoltaic cells, whether or not assembled in modules or made up into panels. Where supplied along with a taxable service specified at S. No. 38 of Notification No. 11/2017-Central Tax (Rate) dated 28.06.2017, 70% of the gross consideration is deemed to be the value of goods and 30% the value of the service. | 5% |
Schedule II — Scrap, Waste & Residue Taxable at 18%
Total GST 18% (CGST 9% + SGST 9%) | Notification No. 9/2025-CT(Rate) dated 17.09.2025
| S. No.* | HSN Code | Description of Goods | GST Rate |
| 20 | 2619 | Slag, dross (other than granulated slag), scalings and other waste from the manufacture of iron or steel, other than Linz-Donawitz (LD) slag | 18% |
| 21 | 2620 | Slag, ash and residues (other than from the manufacture of iron or steel) containing metals, arsenic or their compounds | 18% |
| 22 | 2621 | Other slag and ash, including seaweed ash (kelp); ash and residues from the incineration of municipal waste [other than fly ash] | 18% |
| 29 | 2710 | Petroleum oils and oils obtained from bituminous minerals, other than crude; preparations n.e.s. containing 70% or more by weight of such oils as basic constituents; waste oils; Avgas [excluding items outside GST (petrol, diesel, ATF) and PDS kerosene] | 18% |
| 32 | 2713 | Petroleum coke, petroleum bitumen and other residues of petroleum oils or of oils obtained from bituminous minerals | 18% |
| 111 | 3825 | Residual products of the chemical or allied industries, not elsewhere specified or included [except municipal waste, sewage sludge and other wastes specified in Note 6 to Chapter 38] | 18% |
| 116 | 3915 | Waste, parings and scrap, of plastics | 18% |
| 130 | 4004 | Powders and granules obtained from waste, parings and scrap of rubber (other than hard rubber) | 18% |
| 143 | 4017 | Hard rubber (e.g. ebonite) in all forms, other than waste and scrap; articles of hard rubber | 18% |
| 165 | 4501 | Waste cork; crushed, granulated or ground cork | 18% |
| 224 | 6808 | Panels, boards, tiles, blocks and similar articles of vegetable fibre, of straw or of shavings, chips, particles, sawdust or other waste of wood, agglomerated with cement, plaster or other mineral binders | 18% |
| 263 | 7204 | Ferrous waste and scrap; re-melting scrap ingots of iron or steel | 18% |
| 309 | 7404 | Copper waste and scrap | 18% |
| 324 | 7503 | Nickel waste and scrap | 18% |
| 331 | 7602 | Aluminium waste and scrap | 18% |
| 347 | 7802 | Lead waste and scrap | 18% |
| 351 | 7902 | Zinc waste and scrap | 18% |
| 357 | 8002 | Tin waste and scrap | 18% |
| 360 | 8101 to 8112 | Other base metals, namely tungsten, molybdenum, tantalum, magnesium, cobalt mattes and other intermediate products of cobalt metallurgy, bismuth, cadmium, titanium, zirconium, antimony, manganese, beryllium, chromium, germanium, vanadium, gallium, hafnium, indium, niobium (columbium), rhenium and thallium, and articles thereof, including waste and scrap | 18% |
| 361 | 8113 | Cermets and articles thereof, including waste and scrap | 18% |
| 473 | 84 or 85 | E-waste, i.e. electrical and electronic equipment listed in Schedule I of the E-Waste (Management) Rules, 2016 [G.S.R. 338(E) dated 23.03.2016], whole or in part, if discarded as waste by the consumer or bulk consumer | 18% |
| 521 | 8549 | Electrical and electronic waste and scrap | 18% |
Schedule III — Scrap, Waste & Residue Taxable at 40%
Total GST 40% (CGST 20% + SGST 20%) | Notification No. 9/2025-CT(Rate) dated 17.09.2025
| S. No.* | HSN Code | Description of Goods | GST Rate |
| 15 | 2401 | Unmanufactured tobacco; tobacco refuse [other than tobacco leaves] | 40% |
Schedule IV — Scrap, Waste & Residue Taxable at 3%
Total GST 3% (CGST 1.5% + SGST 1.5%) | Notification No. 9/2025-CT(Rate) dated 17.09.2025
| S. No.* | HSN Code | Description of Goods | GST Rate |
| 2 | 7105 | Dust and powder of natural or synthetic precious or semi-precious stones | 3% |
| 9 | 7112 | Waste and scrap of precious metal or of metal clad with precious metal; other waste and scrap containing precious metal or precious metal compounds, of a kind used principally for the recovery of precious metal | 3% |
Exempt Scrap, Waste & Residue
Nil rate | Notification No. 10/2025-CT(Rate) dated 17.09.2025
| S. No.* | HSN Code | Description of Goods | GST Rate |
| 20 | 0501 | Human hair, unworked, whether or not washed or scoured; waste of human hair | Nil |
| 23 | 0506 | Bones and horn-cores, unworked, defatted, simply prepared (but not cut to shape), treated with acid or gelatinised; powder and waste of these products | Nil |
| 118 | 3825 | Municipal waste, sewage sludge, clinical waste | Nil |
| 140 | 5003 | Silk waste | Nil |
| 143 | 5103 | Waste of wool or of fine or coarse animal hair | Nil |
Key Points to Remember
- Reverse charge: Supplies of certain metal scrap (Chapters 72 to 81) by an unregistered person to a registered person are taxable under reverse charge, and TDS at 2% applies on metal scrap supplies between registered persons (B2B) under Notification No. 25/2024-CT. Check applicability for each transaction.
- Classification first: Scrap generated from an article does not automatically follow the article’s rate; classify the scrap under its own HSN.
- E-waste: Discarded electrical and electronic equipment is taxed at 18% irrespective of the rate applicable to the new equipment.
For GST advisory, classification and compliance support, contact us
Disclaimer: This schedule is prepared for general reference and compliance planning only. HSN classification and the applicable rate should be verified against the relevant Central Tax (Rate) notifications, as amended, before relying on it for any supply, return filing or advisory purpose. Rajput Jain & Associates accepts no responsibility for any loss arising from action taken or not taken on the basis of this document.
IFCCL at P-6/90 (2F), Connaught Circus, New Delhi – 110001 +91-98-11-322-785 | ☎️ 9555 555 480 | email info@caindelhiindia.com | www.caindelhiindia.com
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.