FEMA Export Reporting for Service Exporter w.e.f. 1.10.2026
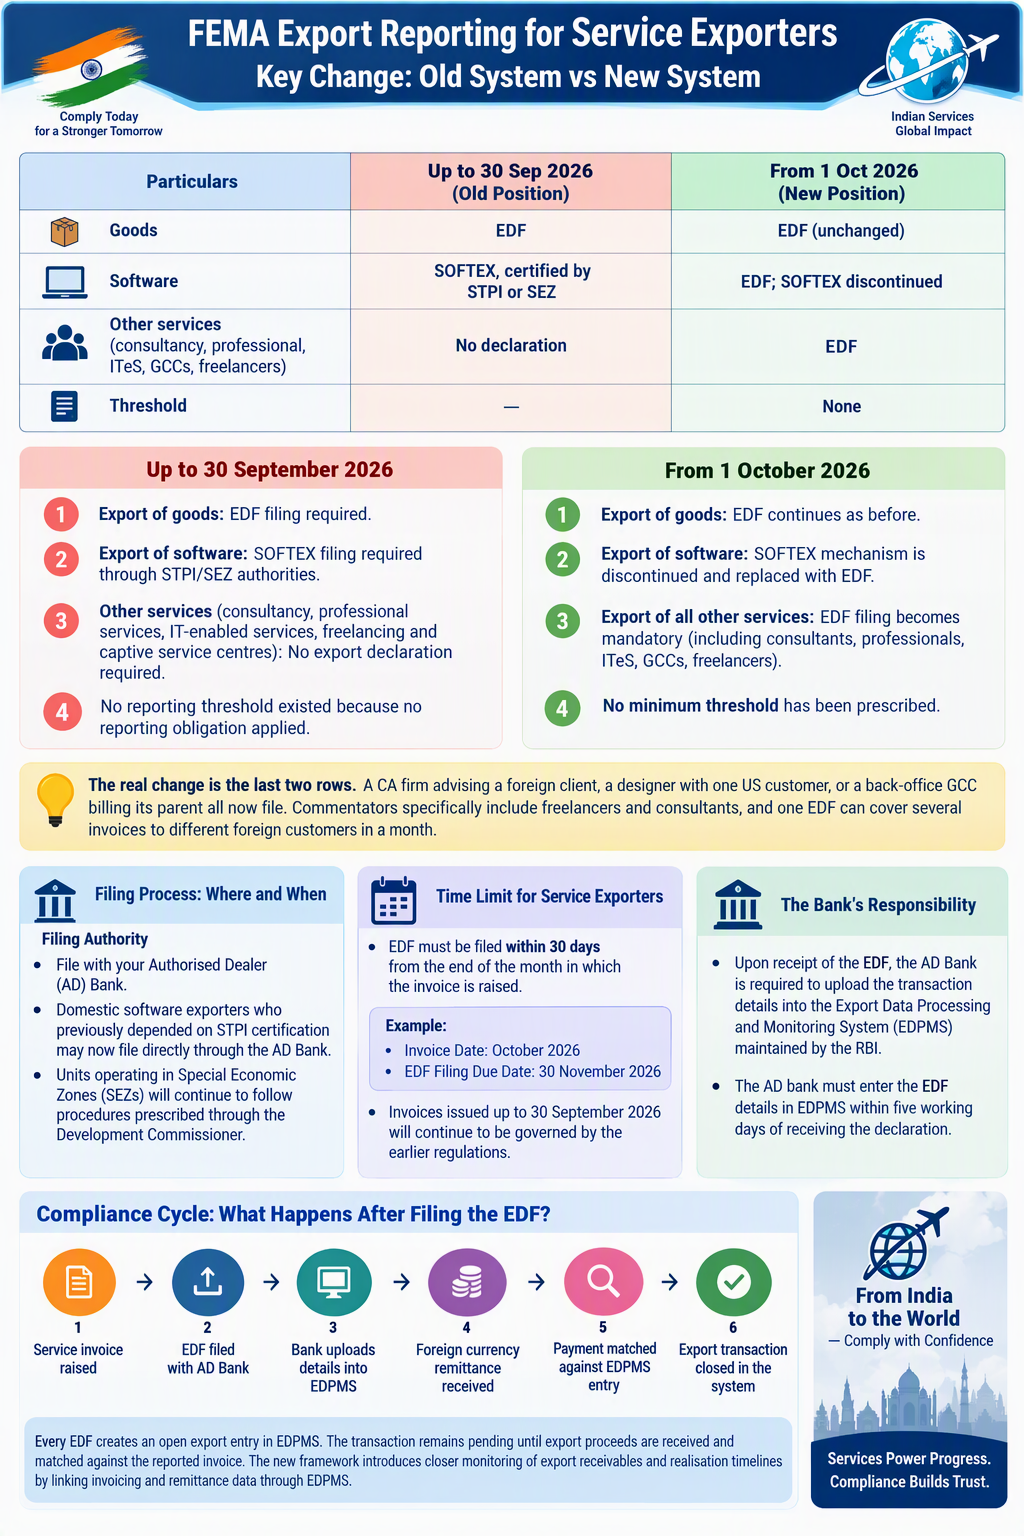
Table of Contents
FEMA Export Reporting for Service Exporters: Major Compliance Change from 1 October 2026
A significant compliance change comes into effect from 1 October 2026 under the Foreign Exchange Management Act (FEMA). Going forward, every Indian business, professional, consultant, freelancer, or service provider raising invoices on overseas clients will be required to report such export transactions to its Authorised Dealer (AD) bank through the Export Declaration Form (EDF). This is a new requirement and marks a notable shift from the earlier framework.
Why This Requirement Has Become Mandatory in case of Export Reporting for Service Exporters
Section 7(3) of FEMA has always required exporters of services to furnish export declarations in the manner prescribed by the Reserve Bank of India. However, until now, the RBI had not prescribed a specific declaration mechanism for most service exports. As a result, there was no practical reporting requirement for ordinary service providers.
This position changes with the introduction of the Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026, notified by the RBI through Notification No. FEMA 23(R)/2026-RB dated 13 January 2026. Effective from 1 October 2026, these regulations replace the 2015 framework and introduce mandatory Export Declaration Form reporting for service exports.
Accordingly, filing Export Declaration Form is no longer a procedural formality requested by banks. It becomes a statutory FEMA obligation, and failure to comply may constitute a FEMA contravention.
Old position versus new position under FEMA Export Reporting for Service Exporters
| Up to 30 Sep 2026 | From 1 Oct 2026 | |
| Goods | Export Declaration Form | Export Declaration Form (unchanged) |
| Software | SOFTEX, certified by STPI or SEZ | Export Declaration Form ; SOFTEX discontinued |
| Other services (consultancy, professional, ITeS, GCCs, freelancers) | No declaration | Export Declaration Form |
| Threshold | — | None |
The real change is the last two rows. A CA firm advising a foreign client, a designer with one US customer, or a back-office GCC billing its parent all now file. Commentators specifically include freelancers and consultants, and one Export Declaration Form can cover several invoices to different foreign customers in a month
Key Change: Old System vs New System in case of FEMA Export Reporting for Service Exporters
Up to 30 September 2026
- Export of goods: EDF filing required.
- The Export of software: SOFTEX filing required through STPI/SEZ authorities.
- Other services such as consultancy, professional services, IT-enabled services, freelancing and captive service centres: No export declaration required.
- No reporting threshold existed because no reporting obligation applied.
From 1 October 2026
- Export of goods: Export Declaration Form continues as before.
- the Export of software: SOFTEX mechanism is discontinued and replaced with Export Declaration Form.
- Export of all other services: Export Declaration Form filing becomes mandatory.
- No minimum threshold has been prescribed.
As a result, even a single overseas invoice issued by a consultant, chartered accountant, advocate, designer, IT professional, freelancer, or Global Capability Centre will require reporting through Export Declaration Form. In many cases, a consolidated monthly EDF may cover multiple invoices issued to different overseas customers during the month.
Filing Process: Where and When in case of Service Exporters
Filing Authority
The declaration must generally be filed with the exporter’s Authorised Dealer (AD) Bank.
- Domestic software exporters who previously depended on STPI certification may now file directly through the AD Bank.
- Units operating in Special Economic Zones (SEZs) will continue to follow procedures prescribed through the Development Commissioner.
Time Limit for Service Exporters
EDF must be filed within 30 days from the end of the month in which the invoice is raised. For example:
- Invoice Date: October 2026
- EDF Filing Due Date: 30 November 2026
Invoices issued up to 30 September 2026 will continue to be governed by the earlier regulations.
The Bank’s Responsibility for FEMA Export Reporting for Service Exporters
Upon receipt of the EDF, the AD Bank is required to upload the transaction details into the Export Data Processing and Monitoring System (EDPMS) maintained by the RBI.
Where and when to file
- Where: With the AD bank. A domestic software exporter that registered with Software Technology Parks of India only to get SOFTEX stands for Software Export Declaration i.e. SOFTEX certified can now file with its AD bank alone, with STPI as an alternative. Special Economic Zone units file with the Development Commissioner.
- When: Within 30 days from the end of the month in which the invoice is raised. For Oct 2026 invoices, the deadline is 30 Nov 2026. Invoices dated up to 30 Sept 2026 stay under the old rules.
- What the bank does: The AD bank must enter the Export Declaration Form details in EDPMS within five working days of receiving the declaration.
What Happens After Filing the Export Declaration Form (EDF)?
Every Export Declaration Form submitted creates an open export entry in EDPMS. The transaction remains pending until export proceeds are received and matched against the reported invoice. The typical compliance cycle will be:
- Service invoice raised.
- EDF filed with AD Bank.
- Bank uploads details into EDPMS.
- Foreign currency remittance received.
- Payment matched against EDPMS entry.
- Export transaction closed in the system.
The new framework introduces closer monitoring of export receivables and realisation timelines by linking invoicing and remittance data through EDPMS.
Consequences of Non-Realisation of Export Proceeds
If export proceeds remain unrealised beyond the permitted period and no extension is obtained, the exporter may face restrictions on future exports. In such cases, subsequent exports may be permitted only against:
- Full advance payment; or
- An irrevocable Letter of Credit.
This mechanism replaces the earlier RBI practice of caution-listing exporters.
FEMA Penalties for Non-Compliance in case of Export Reporting for Service Exporters
Failure to comply with FEMA reporting requirements may attract penalties under Section 13(1) of FEMA as follows:
- up to three times the sum involved where it can be quantified;
- Morover that up to INR2 lakh where it cannot;
- up to INR 5,000 for each day the default continues.
Compounding under Section 15 is available on application. However, the exporter may seek compounding of the offence under Section 15 of FEMA, subject to RBI approval.
Important Additional Points Often Overlooked- Additional Points to Consider
Reduction in Export Realisation Period for Service Exporters
Businesses should note that the RBI has shortened the permissible period for realisation of export proceeds. Following the September 2026 amendment, export proceeds for goods and services must generally be realised within 9 months, while exports invoiced or settled in Indian Rupees must be realised within 12 months. This is a significant change from the original January 2026 Regulations, which prescribed a period of 15 months (18 months for INR-denominated exports). Since many publications and advisories still refer to the earlier timelines, businesses should update their compliance manuals, client communications, and receivables monitoring processes accordingly.
Simplified Closure of Small Outstanding Entries
The revised framework provides relief for small-value transactions by allowing declaration-based closure of EDPMS/IDPMS entries up to ₹10 lakh. This is expected to reduce compliance burden and simplify reconciliation for exporters and importers dealing with low-value transactions.
Possible Relaxation in EDF Filing Timeline
Certain industry commentaries suggest that exporters of non-software services may be permitted to file the EDF on or before the date of receipt of export proceeds, instead of within 30 days from the end of the month of invoicing. However, as this position requires confirmation from the regulatory provisions and the concerned AD Bank, businesses should verify the applicability before relying on such relaxation.
GST Implications of Unrealised Export Receivables
Outstanding export invoices can create implications not only under FEMA but also under GST. Since receipt of consideration in convertible foreign exchange is a key condition for qualifying as an export of services, failure to realise export proceeds within the prescribed period may expose the exporter to GST-related risks in addition to FEMA non-compliance.
Need to Verify Transitional Guidance
Businesses should exercise caution while relying on older articles and guidance notes, as several publications continue to refer to the previous regulatory framework. In particular, some sources still mention continuation of the SOFTEX reporting mechanism for software exporters, despite the broad understanding that the EDF framework will replace SOFTEX from 1 October 2026. Accordingly, exporters should rely on the latest RBI regulations and guidance issued by their Authorised Dealer (AD) Bank.
Practical Action Plan for Businesses
All exporters of services should take the following steps immediately:
- Identify all customers located outside India, even where only a single foreign invoice is issued. Review all foreign invoices and export receivables periodically.
- Establish a monthly EDF filing process with the AD Bank.
- Track filing deadlines and ensure timely submission. Track exports against the revised 9-month realisation timeline.
- Reconcile export remittances against open EDPMS entries every month. Establish a robust EDF filing and EDPMS reconciliation process.
- Monitor outstanding export receivables using the revised 9-month realisation period. Watch for both FEMA and GST implications in cases of delayed or unrealised export proceeds.
- Update engagement letters, compliance manuals and internal SOPs to reflect the new requirements. Verify procedural requirements with the AD Bank during the transition to the new regulatory regime.
Conclusion
From 1 October 2026, FEMA compliance for service exporters enters a new phase. EDF reporting, which was previously relevant mainly for goods exports and software exports, will now extend to virtually all service exporters, including professionals, consultants, freelancers, IT service providers and GCCs. Businesses should proactively establish reporting and receivable-monitoring mechanisms to avoid FEMA contraventions, regulatory restrictions and potential penalties.
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.