Simple Guide for Charitable Trusts & NGOs Form 10B, 10BB
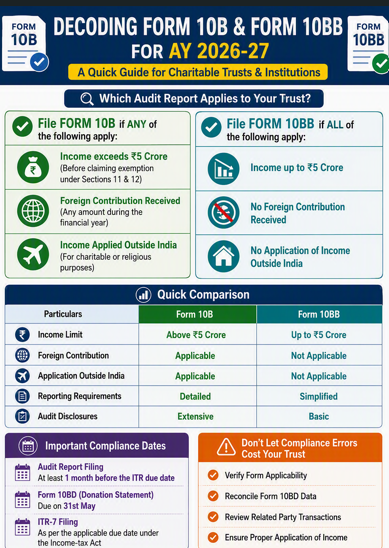
Table of Contents
Simple Guide for Charitable Trusts & NGOs
Form 10B and Form 10BB are audit reports required for trusts and institutions claiming exemption under Sections 11 and 12 of the Income-tax Act. The applicable form depends on the income level and certain activities of the trust.
Which Form Should Be Filed?
File Form 10B if any of the following conditions are satisfied:
- Total income before exemption u/s 11 & 12 exceeds INR 5 Crore
- The trust has received any Foreign Contribution during the year
- Any part of the income has been applied outside India for charitable or religious purposes
- Institutions approved u/s 10(23C) having income above INR 5 Crore also need to file Form 10B.
File Form 10BB if all of the following conditions are satisfied:
- Total income before exemption under Sections 11 & 12 is up to INR 5 Crore
- No Foreign Contribution has been received
- No income has been applied outside India.
Simple Comparison of Form 10B and Form 10BB
| Particulars | Form 10B | Form 10BB |
|---|---|---|
| Income | Above INR 5 Crore | Up to INR 5 Crore |
| Foreign Contribution | Yes | No |
| Application Outside India | Yes | No |
| Reporting Requirements | Detailed | Simplified |
| Compliance Level | Extensive | Basic |
Key Information Required in Form 10B
Form 10B requires detailed reporting on:
Trust Details
- PAN
- Name and Address
- Registration details under 12AB/80G/10(23C)
- Nature of Trust (Trust, Society, Company, etc.)
Management Details
- Trustees
- Founders
- Authors/Settlor
- Directors and Office Bearers
- Related Persons under Section 13(3)
Books of Accounts
- Details of books maintained
- Place where books are kept
- Compliance with Rule 17AA
Donations & Voluntary Contributions
- Form 10BD compliance
- Corpus Donations
- Anonymous Donations
- Foreign Contributions
- Donations not reported in Form 10BD
Application of Income
- Income applied in India
- Income applied outside India
- Corpus utilization
- Loan repayments
- Accumulation under Form 10
- Deemed application through Form 9A
Related Party Transactions
- Loans or benefits given to specified persons
- Salary or remuneration paid
- Property transactions
- Investments in related concerns
Statutory Compliance
- TDS/TCS compliance
- Sections 269SS, 269ST & 269T
- Cash payment violations u/s 40A(3)
- Other law violations, if any
Important Compliance Areas
Before filing Form 10B or 10BB, ensure:
- Registration under Section 12AB is valid
- Form 10BD and donation records are reconciled
- Corpus funds are invested as per Section 11(5)
- TDS has been deducted and deposited wherever applicable
- Related party transactions are properly disclosed
- Application of income is correctly calculated
- Forms 9A and 10 are filed where required
Recent Amendment
From 1 October 2024, approvals u/s 10(23C) are being gradually merged into the registration framework under Sections 11 to 13. Existing approvals remain valid until expiry, but future renewals will generally be under the second regime (Section 12AB).
Key Takeaway
Form 10B is a detailed audit report applicable to larger trusts, trusts receiving foreign contributions, or those applying income outside India. Form 10BB is a simplified audit report applicable to smaller trusts having income up to INR 5 Crore and no foreign contribution or overseas application of income
**********************************************************
If this article has helped you in any way, i would appreciate if you could share/like it or leave a comment. Thank you for visiting my blog.
Legal Disclaimer:
The information / articles & any relies to the comments on this blog are provided purely for informational and educational purposes only & are purely based on my understanding / knowledge. They do noy constitute legal advice or legal opinions. The information / articles and any replies to the comments are intended but not promised or guaranteed to be current, complete, or up-to-date and should in no way be taken as a legal advice or an indication of future results. Therefore, i can not take any responsibility for the results or consequences of any attempt to use or adopt any of the information presented on this blog. You are advised not to act or rely on any information / articles contained without first seeking the advice of a practicing professional.